Lender · Springfield, MO · Member since 2023 · 277 posts · 195 votes
1y
My recommendation would be a 30-year fixed DSCR on each property separately. This allows for more flexibility down the line should they choose to refinance or sell one property, but not do so with the other (vs. a blanket loan that ties the properties together and which may have a release premium).
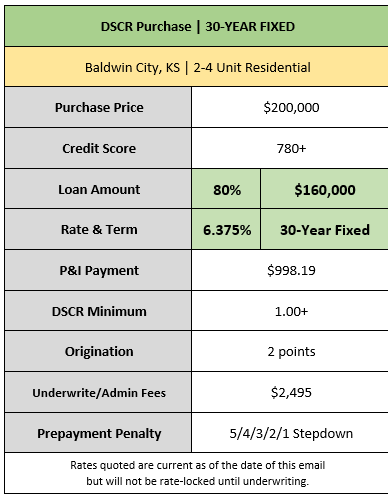
Here's a quick example of what 2-4 unit residential loans would look like for buyers as long as the appraisals come back marked suburban (not rural - rural-marked appraisals will be capped at 65% LTV).
With Baker University nearby, I think there's a good chance these don't come back marked as rural even though the town is smaller. Any buyers should be eligible for the loans below, pending credit and asset verification.
I’m working with Invecstors who want to sell a 4-plex and 3-plex together on neighboring parcels in Baldwin City, Kansas.
Total 7 units, being offered as one package.
Would this be better financed with a commercial loan, or with two conventional loans (one for each parcel)?
Curious what lenders here have seen work best and why.
Also, does anyone here actively lend on this type of property in Baldwin City, KS?
Thanks in advance for any insight!
-- Maddy
Licensed Agent, KS & MO | The Bridge Team / 1st Class Real Estate KC
If they are on separate parcels, it might be more favorable to finance individually on a DSCR loan. The drawback is that most lenders will use the sales comparison approach to determine value. The process, rate, and terms might be better though.
There are a handful of commercial lenders that can do residential portfolios, however they are far few and between. It may require a bit of digging and normally the rate is only fixed for 5-10 years max on a 25 year amortization instead of 30.
We've got the 3-plex + 4-plex package priced at $725k. Current NOI is around $29k, with projected/stabilized NOI closer to $53k once fully leased and with a couple units finishing renovation. 4/7 leases were just renewed close to market rent, but not as high as are updated units are projected. 3 vacant, 1 just renovated now being marketed for rent and should be occupied prior to closing. 2 will likely be renovated prior to close, but not sure they will be occupied w/ rents in place prior to closing.
Would this type of situation still qualify for two separate DSCR loans (one for each parcel), or would the combination of rehabbed units and slightly under-market leases in place on 3 units make approval more difficult?
And more generally — is there a max purchase price or loan size that DSCR programs will allow on 2–4 unit properties?
Rental Property Investor · Philadelphia, PA · Member since 2021 · 774 posts · 500 votes
1y
@Maddy Morell - If you're able to drive up the NOI that much (29k to 53k) would you consider a refinance when that is done? Just thinking that perhaps a commercial loan (once stablized) might generate enough pay off/cash out to pay off the loan/loans from the purcahse. If that is a strategy you want to consider, I think you'll want a loan (or two loans) at purcahse with little/no pre payment penalty. Just my two cents... Good Luck! Greg
We've got the 3-plex + 4-plex package priced at $725k. Current NOI is around $29k, with projected/stabilized NOI closer to $53k once fully leased and with a couple units finishing renovation. 4/7 leases were just renewed close to market rent, but not as high as are updated units are projected. 3 vacant, 1 just renovated now being marketed for rent and should be occupied prior to closing. 2 will likely be renovated prior to close, but not sure they will be occupied w/ rents in place prior to closing.
Would this type of situation still qualify for two separate DSCR loans (one for each parcel), or would the combination of rehabbed units and slightly under-market leases in place on 3 units make approval more difficult?
And more generally — is there a max purchase price or loan size that DSCR programs will allow on 2–4 unit properties?
You'll get better pricing doing two separate 2-4 unit DSCR loans and won't have the same issues you'd run into with multiple vacant units. DSCR loan maxes vary from lender to lender but generally you can get $3.5 million+ DSCR loans
Kansas City · Member since 2025 · 25 posts · 3 votes
1y
@Erik Estrada -- Thats what I was thinking as well. Appreciate your insight!
These are on separate parcels, so 2 DSCR loans will likely be the cleaner path, especially if the comp approach is what's driving value.
The seller also owns an 8-unit in the same town that’s fully leased, though I don’t believe it traded on-market. There aren’t many other multifamily sales in Baldwin City to lean on for comps. Do you think that will affect ability to appraise these?
Also - are you a commercial lender who also does residential portfolios, or do you have contacts in that space? I’d love to get a sense of options if a buyer wanted to bundle this package differently!
Hey Maddy!
If it is an 8 unit building, then a commercial appraisal will be ordered. They will heavily emphasize the income approach for value. If there are few comps in the area it may impact the report yes. But honestly appraisers in this space have to be a lot more thorough on their analysis. I find that some residential appraisers are a hit or miss, compared to commercial.
We do portfolio lending, 1-4 Residential, 5-21 unit multi family, and some mixed-use.
Kansas City · Member since 2025 · 25 posts · 3 votes
1y
@Greg Kasmer - Thanks Greg, that makes a lot of sense. In this case, I’m representing the Seller rather than holding the property myself, so a refinance isn’t in the cards. He purchased this year and has put quite a bit into updates/renewals on exterior and completed 1 unit - plan to update 2 more, and pass it along with some remaining value-add upside for the next buyer.
Current NOI is sitting around $29k with several units vacant or under-market. Stabilized projections are closer to $53k once the last few renovations are complete and it's fully leased up. We should see some of that NOI increase even before closing as the updated units get occupied!
Appreciate the insight on pre-payment penalties — definitely a good point for a buyer considering DSCR or conventional on separate parcels.
Kansas City · Member since 2025 · 25 posts · 3 votes
1y
@Zachary Deal Good to know — appreciate that insight. I figured splitting into two DSCR loans could definitely be a cleaner path, especially with a few units still vacant. Seller hadn't considered this, was just thinking we'd sell as a package commercially - so great to hear! Helpful to hear the loan size ceiling is higher than I realized too. Thanks!