Nobody is talking about the real impact of inflation

Nobody is talking about the real impact of inflation

Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes

Predictions for inflation have been around for years, now it's here and it will be for a while. It's in the news every day. CPI (consumer Price Index) came out a few days ago with 7.0%  for 2021 and when I look at the producer price index at 9.7% - biggest gain on record - it seems like there will be more to come. And this is global: Germany 5.3%, India 7.6%, Mexico 7.3%, Brazil 10%, Russia 8.4% (and then the catastrophic inflation in Turkey 36% and Argentina 51%)!

The current situation of 30y fixed rates being less than half of what inflation is seems absurd! Rates should be higher than inflation! This is upside down, how can lenders sustain this?

On top of that RE keeps appreciation - and from what it looks like - it will have to continue down this path. Many of us wish we could go back to 2009-2012 as the opportunity of a lifetime and buy more then - we might be looking back at 2022 the same way.

The general public's view on inflation is that it means price increases; gas, steaks, houses. Those are all short term inconviniences. Nobody is talking about that fact that their 401k just lost 7% and will probably continue to do so potentially year over year compounding down.

It also means that real estate got 7% cheaper, which offsets about a thrid of the national appreciation gain last year (about 20%). What puzzels me is that inflation with it's massive impact on REI is not a big topic here on BP.

I am on here every morning and there are still so many posts about when is the housing market going to crash and barely anything about inflation. This is a literal game changer. What type of rent growth will we see over the next five years. Try running numbers with 5% p.a. Inflation could be the best thing that happenes to anyone with a sizeable portfolio, it could also get really ugly if it starts to run away. 

Where will interest rates be in 5 years? Could we see double digits again? The current consesus is that we will see mortageg rates at 3.7% by the end of the year and I don't believe it. I am surprised there is no fear mongering about the crash of the USD. How wide can the wealth devide grow, before the tension gets too high? What gives? Where are all my fellow YouTubers - seems like the next big clickbait! Or will that still come?

Anyway, just some thoughts along my cup of coffee - time to get to work! 
11Reply
121 views

Most Popular Reply

Rental Property Investor · Erie, PA · Member since 2015 · 1k+ posts · 2k+ votes
4y

Ken McElroy and Robert Kiyosaki talks about inflation all the time, including the wealth gap and what socialism/communism would do to landlords/the wealthy and so I get my fill of it listening to them and their guests. 

You're right - people don't talk much about inflation on here excluding the 'things cost more' statements I typically see.

I recently bought some value-add properties that are under market. Rents are going up and if any tenants want to leave I'm cool with that as I will be able to get market rent. 

Undermarket rents+ inflation = wowza

Yes - I think about the things you're talking about. Mainly the wealth divide and the threat of rent freezes and other governmental controls that could be even worse than rent freezing. Society won't be talking about how the Federal Reserve debased our currency due to the fact our clown government can't ever balance a budget... they'll instead target "greedy landlords" and will impact us in a negative way, no doubt. 

The government creates all the problems and then they pass the blame onto someone else.

See this reply in the discussion

44 Replies

Jump to latestLatest
  • Joe VilleneuvePro Member
    Plymouth, MI · Member since 2013 · 13k+ posts · 19k+ votes
    4y

    How does RE get cheaper and appreciate at the same time?

  • Rental Property Investor · Erie, PA · Member since 2015 · 1k+ posts · 2k+ votes
    4y

    Ken McElroy and Robert Kiyosaki talks about inflation all the time, including the wealth gap and what socialism/communism would do to landlords/the wealthy and so I get my fill of it listening to them and their guests. 

    You're right - people don't talk much about inflation on here excluding the 'things cost more' statements I typically see.

    I recently bought some value-add properties that are under market. Rents are going up and if any tenants want to leave I'm cool with that as I will be able to get market rent. 

    Undermarket rents+ inflation = wowza

    Yes - I think about the things you're talking about. Mainly the wealth divide and the threat of rent freezes and other governmental controls that could be even worse than rent freezing. Society won't be talking about how the Federal Reserve debased our currency due to the fact our clown government can't ever balance a budget... they'll instead target "greedy landlords" and will impact us in a negative way, no doubt. 

    The government creates all the problems and then they pass the blame onto someone else.

  • Real Estate Broker · Milwaukee, WI · Member since 2016 · 121 posts · 81 votes
    4y
    Originally posted by @Karl B.:

    Mainly the wealth divide and the threat of rent freezes and other governmental controls that could be even worse than rent freezing. Society won't be talking about how the Federal Reserve debased our currency due to the fact our clown government can't ever balance a budget... they'll instead target "greedy landlords" and will impact us in a negative way, no doubt. 

    The government creates all the problems and then they pass the blame onto someone else.


    Completely agree. The powers that be always try to keep the crabs fighting rather than focused on escaping the bucket... Though the BTC community has certainly shed a ton of light on how our currency isn't actual money anymore.


    @Marcus Auerbach, like you said, the fact that interest rates are under the rate of inflation is bonkers. But then again, the US/IMF/FedReserve don't have a sound monetary theory; it's all funny money where those that control the money printer have decided to print as much as they wish. EVERY fiat currency goes to zero and that's exactly what we're about to see playout in front of us. This is the fourth iteration of a central bank in the US and it will see the same result as the previous three, extinction. Additionally, the parrallels to the early stages of the Weimar Republic are undeniable. But we're not there yet, so as long as this horse and pony show continues, keep trading your funny-paper for hard assets as quickly as possible. Lock in those 30year notes!!

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    4y
    Originally posted by @Joe Villeneuve:

    How does RE get cheaper and appreciate at the same time?

    It doesn't - excuse my poor wording. Coffee takes a while to kick in. 7% of whatever you locally have seen for appreciation is just devaluation of paper dollars. So it the case of Milwaukee, about half of the "appreciation" measured in dollars last year was just inflation. So it went up only half as much as people think, which is relativley cheaper.

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    4y
    Originally posted by @Karl B.:

    Ken McElroy and Robert Kiyosaki talks about inflation all the time, including the wealth gap and what socialism/communism would do to landlords/the wealthy and so I get my fill of it listening to them and their guests. 

    You're right - people don't talk much about inflation on here excluding the 'things cost more' statements I typically see.

    I recently bought some value-add properties that are under market. Rents are going up and if any tenants want to leave I'm cool with that as I will be able to get market rent. 

    Undermarket rents+ inflation = wowza

    Yes - I think about the things you're talking about. Mainly the wealth divide and the threat of rent freezes and other governmental controls that could be even worse than rent freezing. Society won't be talking about how the Federal Reserve debased our currency due to the fact our clown government can't ever balance a budget... they'll instead target "greedy landlords" and will impact us in a negative way, no doubt. 

    The government creates all the problems and then they pass the blame onto someone else.

    Robert Kyosaki, I hate to say it, is a one hit wonder. He wrote a great book a long time ago and has spent the last 20 years shamelessly milking young investors through Rich Dad Education. He is one of the most consistent fear mongerers out there - predicting a crash as long as I have been in RE - and really just selling his stuff. New book, BTW.

    Ken McElroy, where to start? Same, basically. Just watch his YouTube videos from 2020 and 2021. I am surprised he did not delete them, or did he?  Same concept, monetizing fear. Both have an anti-goverment redderic that is just not useful or constructive; basically unchanged since the 90s, no matter who was president. Also, socialism and communism are radically different concepts and I know in the US we use them interchangably.

    But my post was not about politics (we have issues, and so does the rest of the world currently, no matter of capitalist, socialist or communist country - all have the same problems at the moment, interesting to note). 

    It's not only landlords who have created massive wealth last year - every homeowner did. 50k to 100k in most states on average. Tax free BTW. That is half a life worth of savings for many workers who rent. And I can't see that go well for long... But it also poses great opportunity for those who know how to seize it. it's just a really big topic and it will define us for the next decade!

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    4y

    @Jeremy Trad - I was not ready to put the Weimarer Republik out there, but yeah..

  • Bruce WoodruffPro Member
    Contractor/Investor/Consultant · San Diego / Phoenix · Member since 2021 · 12k+ posts · 15k+ votes
    4y

    What kills me about the inflation thing is that they no longer count energy and food. They went to this core inflation BS to save face for past administrations. When you add in these factors, what is our inflation today? 20+%.......?

  • Investor · Youngstown, OH · Member since 2017 · 2k+ posts · 2k+ votes
    4y

    I wouldn't say no one is talking about it. It's been discussed frequently on the BP RE podcast over the last few months.

  • Real Estate Broker · Milwaukee, WI · Member since 2016 · 121 posts · 81 votes
    4y
    Originally posted by @Marcus Auerbach:

    @Jeremy Trad - I was not ready to put the Weimarer Republik out there, but yeah..

    I think the main difference here(USA vs WR) is that USD also serves as the global reserve currency, not just domestic. What I'm still working through is if that will cause the inflation bomb to accelerate faster (ie: hyperinflation and loss of confidence in the currency) or if it will extend the dying process through a few more boom/bust cycles before finally crashing (which would result from the current monetary policy folks continually tampering with the controls trying to delay the inevitable free market forces.) I tend to lean toward the latter outcome being more probable, which provokes the questions: "how many more boom/bust cycles do we have left before there's a complete loss of confidence?", "what will the final boom/bust cycle look like?", and "what is the best tool to store my wealth through that perceived eventuality that I have access to today?"


    Also, completely agree that Kiyosaki & McElroy lean a bit too heavily on the tactic of fear-driven sales. A crash will certainly be coming, but it's because of the money printing, not "all the pent of forbearance which will lead to a huge foreclosure market" that was spouted in late 2020 and early 2021. Different crash scenarios require different responses and I think the idea of holding larger cash positions to capitalize on a larger foreclosure market is foolish when the value of the dollar is rapidly collapsing. That being said, I still value the fact that they're willing to put their opinion out there (it's a great way to reflect and stress-test your own ideas.)

  • Investor · MI · Member since 2018 · 37 posts · 40 votes
    4y

    I'm personally pretty bullish on GDP growth largely driven by tech, etc in the US, especially with trends from covid. If bullish on that, then I don't see many structural indicators of a market crash. Fed printed ~$150 Billion USD in 2020 (correct if anyone has different figure) and total wealth in the US is estimated ~$140 Trillion. Debt to GDP ratio is 122% in 2021 (down from 129% 2020), which is historically high but if bullish on next decade of economic growth from tech, etc, I don't expect that being an issue. If not bullish on economic growth, if some "black swan" occurs, etc then, of course, we might see big issues. 

    I need to think more / research more about wealth inequality esp since 2020, how much worse it's gotten, etc. It seems that wages, esp. at lower levels, have raised significantly since pre-covid. There may need to be more of a "rebalancing", but I see that more likely in the form of broad based measures (print more money to subsidize lower earners, increase taxes, etc) - which fundamentally, I don't see being catastrophic in light of being bullish on next decade of economic growth. 

    I see continued measures to increase ability to build homes (ADU laws many cities are adopting, rules like SB9 and SB10 in California, etc) being adopted by more cities in a more aggressive manner as being more likely than extreme (or even moderate) broad based rent controls.

    I think automation of home building technology (many off-site 3D printing players, some on site automation tech for construction of tract homes) will be a real factor in the next 3 to 10 years that will be the primary/only saving grace to actually make housing more affordable (easiest way to meaningfully decrease build costs). While no one has figured it out yet, there are a lot of interesting VC backed companies, and I do think/hope that 1 or multiple can make a dent in getting build costs from $X to a meaningfully lower % of current $X. TVs, computers, etc have gone down significantly in price since inception because of Moore's law - that hasn't happened yet with tech being applied to real estate construction - when/as it does get applied, it's worth tracking as real estate investors.

    Given all the above, since I don't think a near term market crash is likely, inflation over the coming years is likely a very good thing for any of us holding RE portfolios. With that said, I don't actually think inflation forecasts for 2022 - 2025 are that high - believe I've seen 2% - 3%ish expectations, but we'll see. 

    Think it is easier to talk about these type of things w/ specifics rather than in abstract, but curious others' takes on this (all my thoughts subject to change / open to feedback).  

  • Investor · Milwaukee - Mequon, WI · Member since 2010 · 5k+ posts · 7k+ votes
    4y

    @Nick H. - a near term market crash seems unlikely, agreed, in particular if you refer to the housing market. But I think it's very possible that we could see a technical recession, a kind of a hang over from the covid stimulus. That will slow other markets, in particular the stock market!

    @Jeremy Trad - very well said: Different crash scenarios require different responses and I think the idea of holding larger cash positions to capitalize on a larger foreclosure market is foolish when the value of the dollar is rapidly collapsing.

  • Queen Creek, AZ · Member since 2014 · 2k+ posts · 1k+ votes
    4y

    In 2021 inflation was up 7%, more if you count the impact of rising food and energy prices on consumers.  Wages were up 5%.  The 2% spread means that consumers will spend more but get less "stuff".  Most consumers will find a way to get by, but a 2% drop in the quantity of "stuff" means manufactures will have to layoff employees. That will be the beginning of the recession, I believe it will start in 2022.

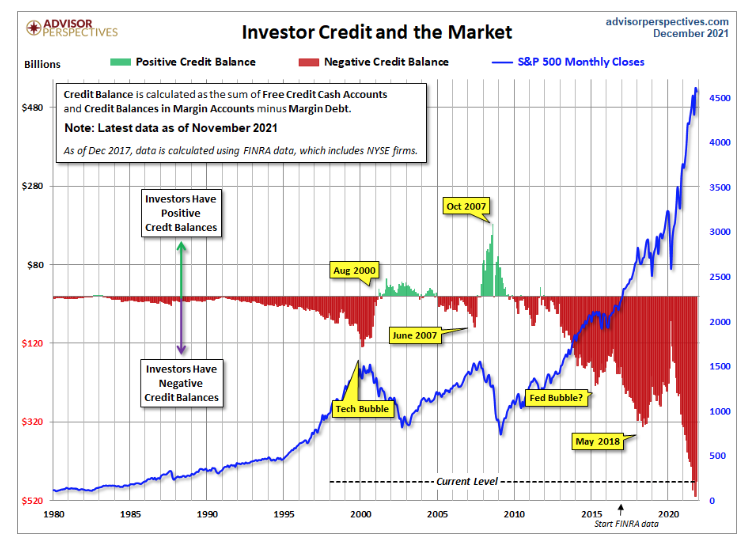
    Adding to the overall misery, stocks are at record highs, but so is margin debt. When the economy starts to contract investors will look at the rising cost of margin debt and the weakening economy and start to deleverage out of stocks, this will cause stocks to drop, resulting in more deleveraging. The AMC theaters, Game Stop's, and Blackberries of the world will look a lot less attractive to the speculators that have driven them up.

  • Investor · Philadelphia, PA · Member since 2015 · 3k+ posts · 3k+ votes
    4y

    I prefer the Mustachian view on inflation - much less alarmist.

  • Bruce WoodruffPro Member
    Contractor/Investor/Consultant · San Diego / Phoenix · Member since 2021 · 12k+ posts · 15k+ votes
    4y
    Originally posted by @Max T.:

    I prefer the Mustachian view on inflation - much less alarmist.

     It may be less alarming, but does that mean it's right? A quick read found lots of factual holes and opinion in the story....

  • Investor · Philadelphia, PA · Member since 2015 · 3k+ posts · 3k+ votes
    4y
    Originally posted by @Bruce Woodruff:
    Originally posted by @Max T.:

    I prefer the Mustachian view on inflation - much less alarmist.

     It may be less alarming, but does that mean it's right? A quick read found lots of factual holes and opinion in the story....

     Inflation is easy Bruce. Just raise rent. And spend less time on bigger pockets :-)

  • Bruce WoodruffPro Member
    Contractor/Investor/Consultant · San Diego / Phoenix · Member since 2021 · 12k+ posts · 15k+ votes
    4y

    Raise rents, yes! BP gets a morning nod while I sip some coffee, I think that'll have to stay.... :-)

  • Investor · Rochester, NY · Member since 2016 · 576 posts · 358 votes
    4y

    Thanks for the post! I don't have anything to add.

    Maybe you don't see it addressed here because we're so busy with the day-to-day, that we don't have time to think about it. Thanks for giving me something to think about.

  • Investor · MI · Member since 2018 · 37 posts · 40 votes
    4y
    Originally posted by @Max T.:

    I prefer the Mustachian view on inflation - much less alarmist.

    Yup agreed that this is a much more thoughtful/analytical/accurate review. Need to look at actual inputs (inflation we expect, nominal GDP growth we expect, and therefore real GDP growth we expect, etc) to have any credible argument here. IMO Mustuach does a good job of laying that out.  

  • Edmond, OK · Member since 2012 · 456 posts · 270 votes
    4y

    @Marcus Auerbach

    Also, consider that inflation higher than the desired norm (2%) is not a guarantee, it can come down in future years.

  • Investor · Sugar Hill, GA · Member since 2014 · 168 posts · 97 votes
    4y

    @Marcus Auerbach

    I was actually thinking the same thing.

    A 7% inflation is something to take into account when making decisions in real estate and while that inflation rate is unlikely to repeat itself in 2022

    It will be most likely higher than the 3.5 % you would pay for a conventional loan.

    To spell it out: one can get a loan today which will be essentially interest free for at least a year.

  • Investor · Central Virginia · Member since 2020 · 394 posts · 253 votes
    4y

    "What puzzels me is that inflation with it's massive impact on REI is not a big topic here on BP." I would say that this is probably because RE is an asset - which typically improve in inflationary times.

  • Investor · Central Virginia · Member since 2020 · 394 posts · 253 votes
    4y

    Hi @Bob E., you mention margin debt. I am curious if you think that investors using BRRR are considered marginal investors. They typically uses short term debt to finance deals, right? With rising construction costs are they going to be left holding the bag in the near term?

    What are your thoughts?

    Thanks in advance. 

  • Queen Creek, AZ · Member since 2014 · 2k+ posts · 1k+ votes
    4y

    @Chris Webb Hi Chris, I was actually referring to Margin Debt in stock brokerage accounts, where your stock acts as collateral for the loan. I believe most of this money is being used to buy stocks, probably a lot of the investors that have driven up GameStop (GME) Blackberry (BB) AMC Theaters (AMC) are using margin. I am not sure if margin can be used to buy Crypto but it is possible that is being fueled with margin debt as well.

    I use margin debt as a LOC that I draw on to make purchases and then refi latter, my margin rate is 3.35%. I am working to refi the majority of that into a 10 year commercial loan by leveraging a small apartment building.

    The risk with margin debt is that the amount you can borrow is tied to the value of your stocks.  For example, if you have 100k you can usually borrow 50k on margin.  If you borrow 50k and your stock loses 10% your new margin limi is 45k.  If you borrowed the 50k limit your broker gives you 3 days to reduce your margin amount.  You can deposit 5k cash or sell some of your stock.  If a lot of people have to sell stock that pushes the price of the shares down.  This is what happened during the great depression, people bought stock on margin but the loans were 90% of the purchase so with 10k you could buy 100k of stock, then the stock doubled and you can use that equity to buy more.  When everyone tries to sell at once you get the crash of 1929.

    Looking at the below chart it looks to me like the market is highly leveraged and there are more likely to be sellers than buyers.  As Warren Buffet once said, "Be fearful when others are greedy and be greedy when others are fearful".

  • New to Real Estate · Greater Seattle Area · Member since 2021 · 50 posts · 16 votes
    4y
    Originally posted by @Bob E.:

    @Chris Webb Hi Chris, I was actually referring to Margin Debt in stock brokerage accounts, where your stock acts as collateral for the loan. I believe most of this money is being used to buy stocks, probably a lot of the investors that have driven up GameStop (GME) Blackberry (BB) AMC Theaters (AMC) are using margin. I am not sure if margin can be used to buy Crypto but it is possible that is being fueled with margin debt as well.

    I use margin debt as a LOC that I draw on to make purchases and then refi latter, my margin rate is 3.35%. I am working to refi the majority of that into a 10 year commercial loan by leveraging a small apartment building.

    The risk with margin debt is that the amount you can borrow is tied to the value of your stocks.  For example, if you have 100k you can usually borrow 50k on margin.  If you borrow 50k and your stock loses 10% your new margin limi is 45k.  If you borrowed the 50k limit your broker gives you 3 days to reduce your margin amount.  You can deposit 5k cash or sell some of your stock.  If a lot of people have to sell stock that pushes the price of the shares down.  This is what happened during the great depression, people bought stock on margin but the loans were 90% of the purchase so with 10k you could buy 100k of stock, then the stock doubled and you can use that equity to buy more.  When everyone tries to sell at once you get the crash of 1929.

    Looking at the below chart it looks to me like the market is highly leveraged and there are more likely to be sellers than buyers.  As Warren Buffet once said, "Be fearful when others are greedy and be greedy when others are fearful".

    Bob, I used a LOC with my stock portfolio over the summer to fund a Duplex/House Hack remodel.

    I am currently focused on repaying back that LOC as quickly as I can with all my extra funds.

    What are your thoughts on LOC and using leverage? Would you agree that paying this off as quickly as possible is the best use of my extra cash each month?

  • Queen Creek, AZ · Member since 2014 · 2k+ posts · 1k+ votes
    4y

    @Trevor Murphy  I would rank urgency of paying down margin in relation to how much of your margin is being used and how much you have left.  Think of it this way, if the stock market dropped 20%, 30% would that impact you?  Remember 2008-09 how big the market drop was.  I was using more of my line than I was comfortable with so we started working on a cash out refi to replace the variable rate debt with fixed rate.  We are supposed to close tomorrow, fingers crossed.

    Also, It seems highly probably that the next recession will start in 2022.  While I do not know what will happen to RE prices in an environment with high inflation and increasing rates I am confidant that the next recession will create opportunities somewhere.  If you are using a small amount of margin, what is available will be there to take advantage of those opportunities.  in 2000 tech stocks crashed, creating a huge opportunity to buy Amazon, Yahoo  and other tech stocks.  Some had huge upside combining off those lows (yahoo not so much).  in 2007 there was a huge opportunity to buy housing.  Who knows what the next bubble will be to pop but being liquid when that opportunity presents itself will let you brag in 10 years about how you bought at the bottom.  Not everything has to be real estate, if Cryptos are the next crash maybe I will buy some and then sell in a few years and buy RE.  

Join the conversationCreate a free account to reply, vote on answers and follow this thread.