Recast vs Pay-down Economics

Recast vs Pay-down Economics

Rental Property Investor · TX · Member since 2012 · 26 posts · 3 votes

I recently sold a rental property and would like to invest the cash into another rental property that I currently own.  I'm treating this investment essentially like a bond (safe, simi-low return, etc). 

From what I can tell the economics on making a large lump sum pay-down on my current loan all to principal (thus shortening my loan life and greatly reducing the interest paid) ; and the economics of recasting the loan are the same... the recast seems to increase the life of the loan even though you put your lump sum to principal, however, your investment property's cash flow month to month is higher. 

  • So does the interest savings + increased cash flow of a recast equal the larger interest reduction afforded by the normal pay-down? 
  • Has anyone used this strategy to increase their cash-flow and make a humble return on reducing interest over the life of a loan? 

Cheers,

JK

0Reply
71 views

6 Replies

Jump to latestLatest
  • Chris MasonPro Member
    Moderator
    Lender · CA · Member since 2015 · 9k+ posts · 10k+ votes
    7y

    ROI will be equal to the interest rate in either case.

    It's just a question of if you want more cashflow today, or if you want it to be debt free sooner tomorrow.

  • Rental Property Investor · TX · Member since 2012 · 26 posts · 3 votes
    7y

    Good to know. Thanks for your reply. It could offer more flexibility. You could Recast and continue to pay down the loan, but have the availability of cash flow if trouble strikes. One of the reasons it appeals to me. 
  • Rental Property Investor · TX · Member since 2012 · 26 posts · 3 votes
    7y

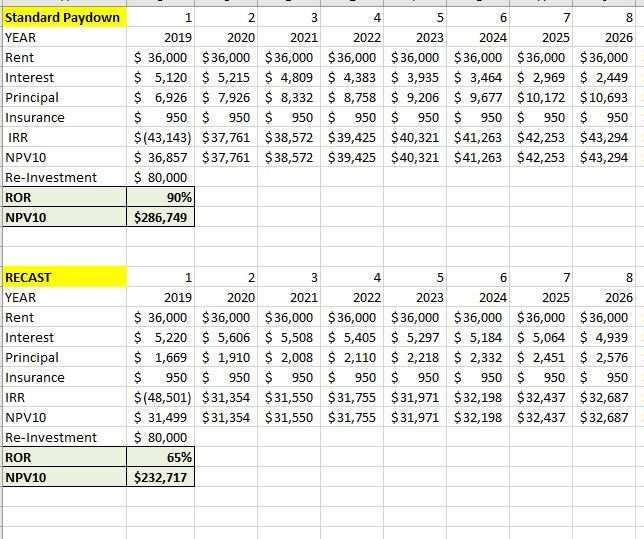
    So I ran two economic cases out to 28 years (only 8 years shown) (Recast vs Standard Pay Down).

    • It seems that if you don't care where what pocket your "gains" are going into (principal vs cash) then the standard pay-down is more adventitious.
      • You'll make less monthly cash-flow, but you'll pay down principal faster with the standard pay down
    • If you "need" the additional flexibility of increased cash flow then the Recast has the advantage.
    • Some items were not included in these economics, but they'll be the same in both cases (taxes, appreciation, inflation, management, etc)
  • Rental Property Investor · Denver, CO · Member since 2015 · 21 posts · 10 votes
    6y
    Originally posted by @Account Closed:

    So I ran two economic cases out to 28 years (only 8 years shown) (Recast vs Standard Pay Down).

    • It seems that if you don't care where what pocket your "gains" are going into (principal vs cash) then the standard pay-down is more adventitious.
      • You'll make less monthly cash-flow, but you'll pay down principal faster with the standard pay down
    • If you "need" the additional flexibility of increased cash flow then the Recast has the advantage.
    • Some items were not included in these economics, but they'll be the same in both cases (taxes, appreciation, inflation, management, etc)

    James, can you share your spreadsheet here?

Join the conversationCreate a free account to reply, vote on answers and follow this thread.