Trying to understand commercial lending for a 5 family

Trying to understand commercial lending for a 5 family

Investor · St Louis MO · Member since 2021 · 4 posts · 1 vote

I keep here you guys talking about commercial lenders not looking at personal finances just the property but why does all the lenders I'm talking to want my personal finances and a personal guarantee on the loan? The property I'm buying is an off market deal with a gross rent of $3,065/month (which is below market) with a cap rate of 12.2% and a net profit of $1,000/month (figured using the Bigger pockets calculator). The purchase price is $175,000 and I'll put 20% down. (I haven't been able to find a lender that will do 10% down) This is the first time I have had to obtain a commercial loan and don't completely understand how this all works.

0Reply
21 views

5 Replies

Jump to latestLatest
  • Lender · Winlock, WA · Member since 2013 · 1k+ posts · 1k+ votes
    4y

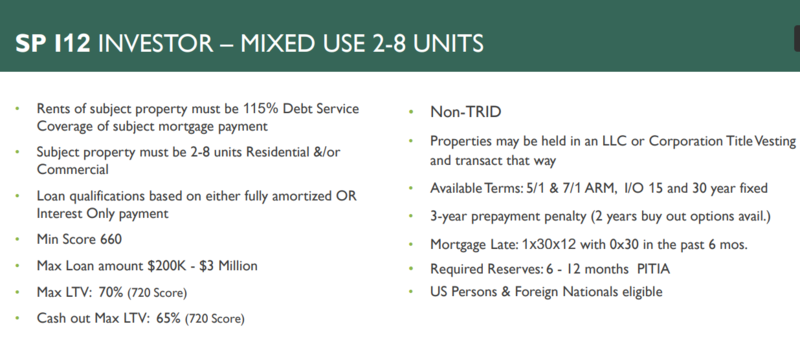
    If you have 30% down on 5-8 units, you can get a DSCR loan. This means the rents must equal 115% or more of the proposed PITI payment. No income or employment is put on the loan, it is purely rents versus payments but you must have 30% for down plus closing costs, or negotiate that the seller pay your closing costs.
  • Deland, FL · Member since 2017 · 2k+ posts · 1k+ votes
    4y
    Originally posted by @Gary Northcutt:

    I keep here you guys talking about commercial lenders not looking at personal finances just the property but why does all the lenders I'm talking to want my personal finances and a personal guarantee on the loan? The property I'm buying is an off market deal with a gross rent of $3,065/month (which is below market) with a cap rate of 12.2% and a net profit of $1,000/month (figured using the Bigger pockets calculator). The purchase price is $175,000 and I'll put 20% down. (I haven't been able to find a lender that will do 10% down) This is the first time I have had to obtain a commercial loan and don't completely understand how this all works.

     I have not heard they don’t require personal guarantee

  • Ned CareyPro Member
    Moderator
    Investor · Baltimore, MD · Member since 2008 · 17k+ posts · 13k+ votes
    4y

    @Gary Northcutt I don't know who is saying that commercial lenders don't look at your personal finances but that is misleading. 

    Most commercial lenders are looking at the income the property generates. However the vast majority of commercial loans will also look at your personal finances. The may not be the primary determination if you get the loan but it is a factor. 

    Contrary to what many people think, most commercial loans will require a personal guarantee. 

  • Lender · Hackensack, NJ · Member since 2016 · 1k+ posts · 372 votes
    4y

    That loan size is way too small for a non recourse loan so your loan will need a personal guarantee, but shouldn't need personal finances to qualify for a non conventional loan

  • Nick BelskyBusiness Member
    Residential and Commercial Broker · Member since 2021 · 1k+ posts · 704 votes
    4y

    @Gary Northcutt

    Some do, some don't.  Normally, lenders will look at your personal finances to make sure everything is kosher.  It's not normally a major factor, unless you've got a lot of funky stuff going on.  The property is the primary concern and they want to make sure the property will at least hold it value and they will be able to recover their losses if you default.  

    Be ready to fork over some cash for closing.  Normally commercial runs about 2-4 points more to close on.

    Cheers!

    Belsky Mortgage, LLC527 Reviews
Join the conversationCreate a free account to reply, vote on answers and follow this thread.