New 4 Bedroom 2 Bathroom Long Term Rental In Sheboygan, WI

New 4 Bedroom 2 Bathroom Long Term Rental In Sheboygan, WI

Rental Property Investor · WI · Member since 2023 · 192 posts · 144 votes

Investment Info:

Single-family residence buy & hold investment.

Purchase price: $255,000
Cash invested: $76,500

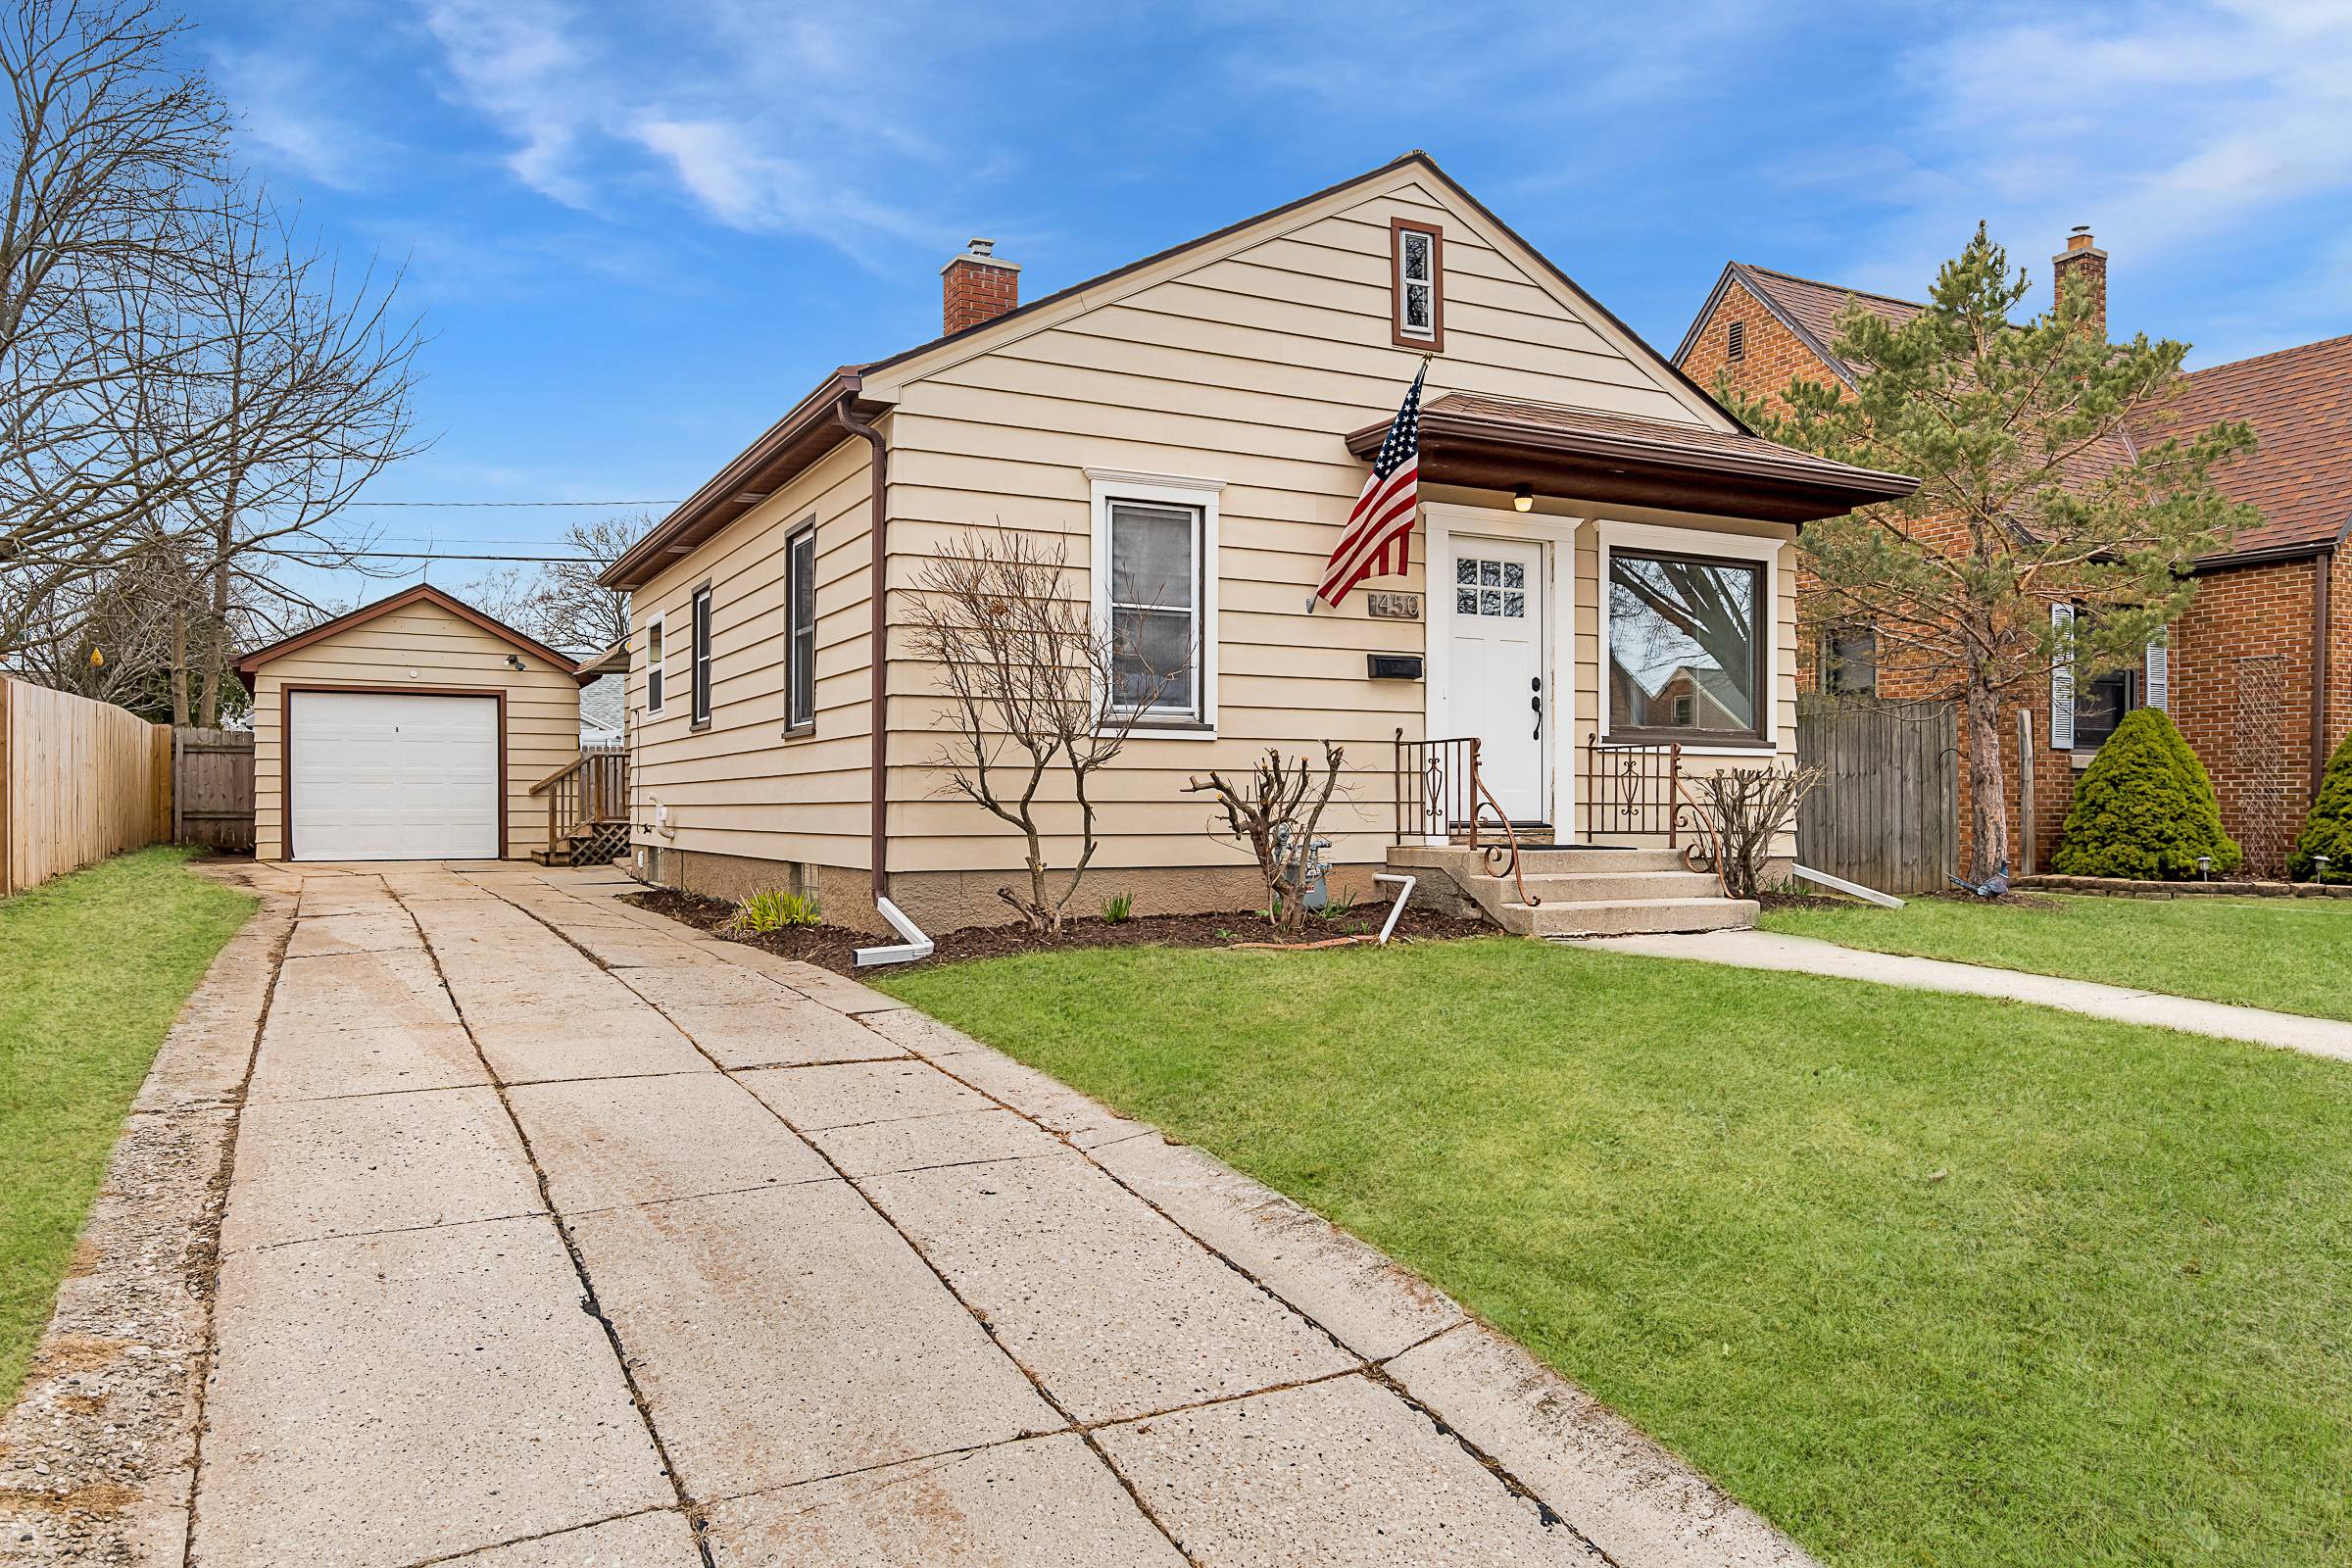
Single family 4 Bedrooms, 2 full bathrooms with detached 1 car garage and off-street parking located in a great neighborhood in Sheboygan. Ranch home with a fenced in backyard. Newly remodeled home fully updated with stove, fridge, dishwasher, microwave, all brand new! Basement partially finished with washer and dryer included.

What made you interested in investing in this type of deal?

Multiple things, this property was in our buy box, we liked the location, we were able to get the property for 9% under it's original asking price, and it was flipped by someone we trust so it doesn't need work. This property also had an accepted offer where the buyer backed out however they paid for the home inspection and the owners did repairs to correct any findings which we didn't have to pay for.

How did you find this deal and how did you negotiate it?

Our real estate agent owned the house, knew what we were looking for, and called to offer it to us. As long as we agreed to the purchase price the house was ours.

How did you finance this deal?

We financed with conventional financing putting 30% down. I was a bit shocked that 20% resulted in 8.125% interest even with an 800 credit score. Putting 30% down and paying an extra $900 in fees we were able to get the rate to 6.875% which was more manageable as a long term rental.

How did you add value to the deal?

With the property already flipped their is limited work to do. We put additional money down to improve cash flow. Other than that with this property our value add was limited.

What was the outcome?

This week we will be listing the property for rent and waiting to place our next set of tenants.

Lessons learned? Challenges?

I think the biggest challenge as this was a pretty simple deal was the sticker shock of the interest rates. I know they are always moving but I was estimating 7% on the high end. I am fortunate enough to have the cash to increase the down payment but if I didn't I would run into cashflow issues with this property. This deal all came together really quickly but in the future I need to find out my rate ahead of time.

Did you work with any real estate professionals (agents, lenders, etc.) that you'd recommend to others?

I worked with Bank First in Sheboygan, WI for financing and Pleasant View Reality in Plymouth, WI for my agent. I HIGHLY recommend both of them. They have now helped us through 7 total properties and we couldn't be happier with their service! If you are looking for a loan officer or real estate agent and are in the Sheboygan area I would recommend Wendy Conto and Matt/Nikki Kapellen!
0Reply
62 views

8 Replies

Jump to latestLatest
  • Jaycee GreenePro Member
    Real Estate Consultant · St. Louis MSA · Member since 2024 · 3k+ posts · 727 votes
    1y
    Quote from @Paul Novak:

    Investment Info:

    Single-family residence buy & hold investment.

    Purchase price: $255,000
    Cash invested: $76,500

    Single family 4 Bedrooms, 2 full bathrooms with detached 1 car garage and off-street parking located in a great neighborhood in Sheboygan. Ranch home with a fenced in backyard. Newly remodeled home fully updated with stove, fridge, dishwasher, microwave, all brand new! Basement partially finished with washer and dryer included.

    What made you interested in investing in this type of deal?

    Multiple things, this property was in our buy box, we liked the location, we were able to get the property for 9% under it's original asking price, and it was flipped by someone we trust so it doesn't need work. This property also had an accepted offer where the buyer backed out however they paid for the home inspection and the owners did repairs to correct any findings which we didn't have to pay for.

    How did you find this deal and how did you negotiate it?

    Our real estate agent owned the house, knew what we were looking for, and called to offer it to us. As long as we agreed to the purchase price the house was ours.

    How did you finance this deal?

    We financed with conventional financing putting 30% down. I was a bit shocked that 20% resulted in 8.125% interest even with an 800 credit score. Putting 30% down and paying an extra $900 in fees we were able to get the rate to 6.875% which was more manageable as a long term rental.

    How did you add value to the deal?

    With the property already flipped their is limited work to do. We put additional money down to improve cash flow. Other than that with this property our value add was limited.

    What was the outcome?

    This week we will be listing the property for rent and waiting to place our next set of tenants.

    Lessons learned? Challenges?

    I think the biggest challenge as this was a pretty simple deal was the sticker shock of the interest rates. I know they are always moving but I was estimating 7% on the high end. I am fortunate enough to have the cash to increase the down payment but if I didn't I would run into cashflow issues with this property. This deal all came together really quickly but in the future I need to find out my rate ahead of time.

    Did you work with any real estate professionals (agents, lenders, etc.) that you'd recommend to others?

    I worked with Bank First in Sheboygan, WI for financing and Pleasant View Reality in Plymouth, WI for my agent. I HIGHLY recommend both of them. They have now helped us through 7 total properties and we couldn't be happier with their service! If you are looking for a loan officer or real estate agent and are in the Sheboygan area I would recommend Wendy Conto and Matt/Nikki Kapellen!

    @Paul Novak Did you have to do any rehab on this property and when did you close on the purchase? 

  • Contractor · Sheboygan, WI · Member since 2016 · 921 posts · 266 votes
    1y

    @Paul Novak how do you anticipate you will have any positive ConC return? At 6.875% your mortgage is $1160/ month. RE taxes are at least $5k and insurance at least another $1k. That totals $1660/ mo with no future consideration for maintenance.

    • Rental Property Investor · WI · Member since 2023 · 192 posts · 144 votes
      1y
      Quote from @Todd Goedeke:

      @Paul Novak how do you anticipate you will have any positive ConC return? At 6.875% your mortgage is $1160/ month. RE taxes are at least $5k and insurance at least another $1k. That totals $1660/ mo with no future consideration for maintenance.


       Todd, good questions.  While this might not work for everyone this situation works for us.  I will go over the deal in further details and explain why it works for us.  My actual mortgage payments are $1,172.  Our property taxes are $2,403 or $200.25 per month.  My insurance costs are $965.39 per year, $80.45 per month.  This puts our total monthly expenses at $1,453.32 and I plan to pay $1,475 per month.  We are going to rent it out at $1,950 per month putting our cash flow at $475 per month.

      My normal cashflow goal when starting out at a minimum is $500 per month to make sure I have enough cashflow to cover maintenance and vacancy.  This property was unique because I feel it's the last property we need to hit our cashflow goal to achieve FIRE.  All we need to do now is pay off our properties and we will be able to retire.  I feel this property can appreciate over time along with grow it's cashflow.  Because this was the last property we needed and we liked the property we purchased it with tighter cashflow.

      Lastly we have a relatively high savings rate and save about 60% of our income.  This allows us to save about $10K per month.  With this level of savings if any maintenance repairs come up with have enough to cover them.  While that might not work for most it works in our situation. 

    • Jaycee GreenePro Member
      Real Estate Consultant · St. Louis MSA · Member since 2024 · 3k+ posts · 727 votes
      1y
      Quote from @Paul Novak:
      Quote from @Todd Goedeke:

      @Paul Novak how do you anticipate you will have any positive ConC return? At 6.875% your mortgage is $1160/ month. RE taxes are at least $5k and insurance at least another $1k. That totals $1660/ mo with no future consideration for maintenance.


       Todd, good questions.  While this might not work for everyone this situation works for us.  I will go over the deal in further details and explain why it works for us.  My actual mortgage payments are $1,172.  Our property taxes are $2,403 or $200.25 per month.  My insurance costs are $965.39 per year, $80.45 per month.  This puts our total monthly expenses at $1,453.32 and I plan to pay $1,475 per month.  We are going to rent it out at $1,950 per month putting our cash flow at $475 per month.

      My normal cashflow goal when starting out at a minimum is $500 per month to make sure I have enough cashflow to cover maintenance and vacancy.  This property was unique because I feel it's the last property we need to hit our cashflow goal to achieve FIRE.  All we need to do now is pay off our properties and we will be able to retire.  I feel this property can appreciate over time along with grow it's cashflow.  Because this was the last property we needed and we liked the property we purchased it with tighter cashflow.

      Lastly we have a relatively high savings rate and save about 60% of our income.  This allows us to save about $10K per month.  With this level of savings if any maintenance repairs come up with have enough to cover them.  While that might not work for most it works in our situation. 

      @Paul Novak Are you holding this property in an LLC and when did you close on the loan with Bank First? If it's in the last year, those sound like HML interest rates.

    • Rental Property Investor · WI · Member since 2023 · 192 posts · 144 votes
      1y
      Quote from @Jaycee Greene:
      Quote from @Paul Novak:
      Quote from @Todd Goedeke:

      @Paul Novak how do you anticipate you will have any positive ConC return? At 6.875% your mortgage is $1160/ month. RE taxes are at least $5k and insurance at least another $1k. That totals $1660/ mo with no future consideration for maintenance.


       Todd, good questions.  While this might not work for everyone this situation works for us.  I will go over the deal in further details and explain why it works for us.  My actual mortgage payments are $1,172.  Our property taxes are $2,403 or $200.25 per month.  My insurance costs are $965.39 per year, $80.45 per month.  This puts our total monthly expenses at $1,453.32 and I plan to pay $1,475 per month.  We are going to rent it out at $1,950 per month putting our cash flow at $475 per month.

      My normal cashflow goal when starting out at a minimum is $500 per month to make sure I have enough cashflow to cover maintenance and vacancy.  This property was unique because I feel it's the last property we need to hit our cashflow goal to achieve FIRE.  All we need to do now is pay off our properties and we will be able to retire.  I feel this property can appreciate over time along with grow it's cashflow.  Because this was the last property we needed and we liked the property we purchased it with tighter cashflow.

      Lastly we have a relatively high savings rate and save about 60% of our income.  This allows us to save about $10K per month.  With this level of savings if any maintenance repairs come up with have enough to cover them.  While that might not work for most it works in our situation. 

      @Paul Novak Are you holding this property in an LLC and when did you close on the loan with Bank First? If it's in the last year, those sound like HML interest rates.


       Jaycee, the properties are in our name and we close on this property June 10th.  We have all of our numbers as I worked on getting them last week but we don't close until early next month.

    • Jaycee GreenePro Member
      Real Estate Consultant · St. Louis MSA · Member since 2024 · 3k+ posts · 727 votes
      1y
      Quote from @Paul Novak:
      Quote from @Jaycee Greene:
      Quote from @Paul Novak:
      Quote from @Todd Goedeke:

      @Paul Novak how do you anticipate you will have any positive ConC return? At 6.875% your mortgage is $1160/ month. RE taxes are at least $5k and insurance at least another $1k. That totals $1660/ mo with no future consideration for maintenance.


       Todd, good questions.  While this might not work for everyone this situation works for us.  I will go over the deal in further details and explain why it works for us.  My actual mortgage payments are $1,172.  Our property taxes are $2,403 or $200.25 per month.  My insurance costs are $965.39 per year, $80.45 per month.  This puts our total monthly expenses at $1,453.32 and I plan to pay $1,475 per month.  We are going to rent it out at $1,950 per month putting our cash flow at $475 per month.

      My normal cashflow goal when starting out at a minimum is $500 per month to make sure I have enough cashflow to cover maintenance and vacancy.  This property was unique because I feel it's the last property we need to hit our cashflow goal to achieve FIRE.  All we need to do now is pay off our properties and we will be able to retire.  I feel this property can appreciate over time along with grow it's cashflow.  Because this was the last property we needed and we liked the property we purchased it with tighter cashflow.

      Lastly we have a relatively high savings rate and save about 60% of our income.  This allows us to save about $10K per month.  With this level of savings if any maintenance repairs come up with have enough to cover them.  While that might not work for most it works in our situation. 

      @Paul Novak Are you holding this property in an LLC and when did you close on the loan with Bank First? If it's in the last year, those sound like HML interest rates.


       Jaycee, the properties are in our name and we close on this property June 10th.  We have all of our numbers as I worked on getting them last week but we don't close until early next month.

      @Paul Novak For what it's worth, I think your "pre-buydown" rate is too high. I have a client that got a loan commitment from a bank in the Northeast this past week on a $425k refi on 3 properties she holds in an LLC. With a 720 FICO, she got quoted 7.24% without any buydowns.

  • Contractor · Sheboygan, WI · Member since 2016 · 921 posts · 266 votes
    1y

    @Paul Novak help fellow readers understand how you are paying a RE tax rate of $9.41/$ 1,000 valuation. I know the tax rate in Sheboygan is over $20/$1,000. You stated you paid $255,000 for the house and your RE taxes are $2,400. 2,400/255=$9.41/1,000. 

    Even if you are evading paying RE taxes on present valuation, once the sales transaction is recorded the new assessed valuation will show an amount based on your purchase.

    It does not appear that you allowed for any vacancy %  and have zero maintenance budget.

    • Rental Property Investor · WI · Member since 2023 · 192 posts · 144 votes
      1y
      Quote from @Todd Goedeke:

      @Paul Novak help fellow readers understand how you are paying a RE tax rate of $9.41/$ 1,000 valuation. I know the tax rate in Sheboygan is over $20/$1,000. You stated you paid $255,000 for the house and your RE taxes are $2,400. 2,400/255=$9.41/1,000. 

      Even if you are evading paying RE taxes on present valuation, once the sales transaction is recorded the new assessed valuation will show an amount based on your purchase.

      It does not appear that you allowed for any vacancy %  and have zero maintenance budget.


      Assessments just came through and we underwent quite a few property tax increases last year.  I am not going to say that they won't go up again next year but I felt like most of the increase have already gone through.  All of our properties are in Sheboygan County and our taxes increased last year anywhere from 14% to 21%.  Heck our primary residence went up 34%!  This property also underwent tax increases last year of 23.5%.  The view below comes directly from the county land records for the property so you can see I am being honest with the $2,400 number.  I rounded to keep the math simple.

      As for accounting for maintenance and vacancy% I ran these numbers on this property much tighter than I normally do because it's the last property I need to purchase in order to have enough cashflow to retire.  I am now pivoting from acquisition mode to dept pay off mode.  I am fortunate enough to save about $120K a year from a combination of excess income from our W2 jobs and profits from our portfolio.  If a maintenance request comes in I could leverage that savings to cover expenses.  I can also so in the 4 years I have done this I have never come across an expense that the profits from my portfolio couldn't cover.  I haven't had to use W2 income to cover expenses.  We expect to pay off our entire portfolio in the next 5-6 years.

      I hope this helps add additional clarity.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.