Government Shutdown and McCarthy Firing Likely Has Direct Impact on Mortgage Rates

Government Shutdown and McCarthy Firing Likely Has Direct Impact on Mortgage Rates

Scott TrenchPro Member
Rental Property Investor · Denver, CO · Member since 2014 · 2k+ posts · 6k+ votes

Everyone has their opinion on politics, so I won't comment on good/bad/ugly happening in Washington, or how things ought to be. I ask that you don't either in replies to this thread. You aren't changing any minds. 

Without getting into the politics, however, it is important to point out and discuss the fact that the political situation impacts investors. That uncertainty around whether the US can avoid a shutdown in a month and a half (when the current short-term deal that got McCarthy fired expires) decreases confidence in US Treasuries and whether debt will be continually serviced. 

The 10-Year Treasury, which has been marching steadily upwards all year, increased from a 4.5% to a 4.8% yield on the news. If a government shutdown continues to be viewed as likely, upward pressure on the yield will continue. 

This will result in mortgage rates spiking, and indeed did, with 30-year rates zooming from ~7.6% to 7.8%. 

Investors beware - even if you end up correct on a bet that the Fed will lower rates in 2024 (which I am not confident in),  you might still see mortgage rates go up if the government can't make a deal in the near-term. A US Credit downgrade, be it because we simply spend too much, and can't balloon the national deficit/debt forever OR a downgrade because we simply can't agree on a budget in the first place result in the same outcome: rising interest rates for US borrowers. 

7Reply
26 views

Most Popular Reply

JD MartinBusiness Member
Moderator
Rock Star Extraordinaire · Northeast, TN · Member since 2015 · 10k+ posts · 17k+ votes
3y
Quote from @Chris Seveney:

@JD Martin

I saw a report today that last 3 years of economic data were off significantly and they revised them. They were off so much I think the number was chances of them being off this much was 1 in 4 billion. Basically saying it’s impossible with out data being manipulated

It’s gonna get a lot worse and people have no clue just thinking everything hunky dory and home values will continue to go up. Curious where all that money comes from when Congress balances a budget and rates are 8%.


 I'm generally a pretty optimistic person when it comes to this stuff but I have started keeping more assets liquid and eliminating some of my leverage that's going to reset in the next 2 years because I'm uncomfortable with how things are going lately. 

Skyline Properties
View Page
See this reply in the discussion

8 Replies

Jump to latestLatest
  • JD MartinBusiness Member
    Moderator
    Rock Star Extraordinaire · Northeast, TN · Member since 2015 · 10k+ posts · 17k+ votes
    3y
    Quote from @Scott Trench:

    Everyone has their opinion on politics, so I won't comment on good/bad/ugly happening in Washington, or how things ought to be. I ask that you don't either in replies to this thread. You aren't changing any minds. 

    Without getting into the politics, however, it is important to point out and discuss the fact that the political situation impacts investors. That uncertainty around whether the US can avoid a shutdown in a month and a half (when the current short-term deal that got McCarthy fired expires) decreases confidence in US Treasuries and whether debt will be continually serviced. 

    The 10-Year Treasury, which has been marching steadily upwards all year, increased from a 4.5% to a 4.8% yield on the news. If a government shutdown continues to be viewed as likely, upward pressure on the yield will continue. 

    This will result in mortgage rates spiking, and indeed did, with 30-year rates zooming from ~7.6% to 7.8%. 

    Investors beware - even if you end up correct on a bet that the Fed will lower rates in 2024 (which I am not confident in),  you might still see mortgage rates go up if the government can't make a deal in the near-term. A US Credit downgrade, be it because we simply spend too much, and can't balloon the national deficit/debt forever OR a downgrade because we simply can't agree on a budget in the first place result in the same outcome: rising interest rates for US borrowers. 


     I agree that this is bad news overall for the economy; in 40 days we're virtually guaranteed to have a government shutdown now. Rates are probably going higher on everything just to price in all this instability. 

    Skyline Properties
    View Page
  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    3y

    @JD Martin

    I saw a report today that last 3 years of economic data were off significantly and they revised them. They were off so much I think the number was chances of them being off this much was 1 in 4 billion. Basically saying it’s impossible with out data being manipulated

    It’s gonna get a lot worse and people have no clue just thinking everything hunky dory and home values will continue to go up. Curious where all that money comes from when Congress balances a budget and rates are 8%.

    7e investments53 Reviews
  • JD MartinBusiness Member
    Moderator
    Rock Star Extraordinaire · Northeast, TN · Member since 2015 · 10k+ posts · 17k+ votes
    3y
    Quote from @Chris Seveney:

    @JD Martin

    I saw a report today that last 3 years of economic data were off significantly and they revised them. They were off so much I think the number was chances of them being off this much was 1 in 4 billion. Basically saying it’s impossible with out data being manipulated

    It’s gonna get a lot worse and people have no clue just thinking everything hunky dory and home values will continue to go up. Curious where all that money comes from when Congress balances a budget and rates are 8%.


     I'm generally a pretty optimistic person when it comes to this stuff but I have started keeping more assets liquid and eliminating some of my leverage that's going to reset in the next 2 years because I'm uncomfortable with how things are going lately. 

    Skyline Properties
    View Page
  • Technology · Dallas, TX · Member since 2022 · 496 posts · 314 votes
    3y
    Quote from @Chris Seveney:

    @JD Martin

    I saw a report today that last 3 years of economic data were off significantly and they revised them. They were off so much I think the number was chances of them being off this much was 1 in 4 billion. Basically saying it’s impossible with out data being manipulated

    It’s gonna get a lot worse and people have no clue just thinking everything hunky dory and home values will continue to go up. Curious where all that money comes from when Congress balances a budget and rates are 8%.

    @Chris Seveney got a link to that report?

    BiggerPockets
  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    3y

    I’ll make a couple separate posts to keep each thought separate.

    Higher inflation and higher interest rates.  That’s great we love it.

    Lower inflation and lower interest rates.  That’s great we love it.    

    There will always be investors and gamblers.  
    If your an investor:

    1.  If you have balloon payments coming up in the next 2 to 3 years you should deal with it, not wait for it.  Talk with your banker about refi early, ask for 7 versus 5 year balloon, if you have 17 years left, refi out to 2@ or 25 for cash flow.  You might argue you have a 3.5% rate and will need to refi to a 7.5% rate.  Do it.  Deal with known risk reward versus what happens to you at refi time in the future.

    2.  Get rid of your dogs.  Weather financial, management, bad neighborhood, etc Improve your risk reward going into uncertain times.  Sell some properties.

    3.  Stop shopping your vendors.  Build a team and loyalty.  Lots of posts shopping their loans for a few interest points.  No team there.  No loyalty from your bank in rough times.  Excess covid money has been spent.  Bankers don’t have those deposits and have to push loans with those funds.  Our banker is not taking on new loan customers.  Customers who bank with them are getting preferred loan approval over customers who only do loans with them. 

    4.   Stick with one bank.  You have 5 properties with 5 different banks.  You can’t cross collateralize.  

    Control your risk.  Both in your investments, financing and team or contractors. Don’t go chasing pennies.  Don’t wait for bad things to happen.  Take charge ahead.  

    Start small and Make Your Big Mistakes Early.

  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    3y

    Politics.  You have to include them at a Large view.

    In one year interest rates can go down to 4%, inflation can go down to 2%.  

    Or in one year inflation and interest will accelerate from this point.  Interest rates can only go up a few more points and a few more years or we go broke as a nation.  

    The 80’s fed rates went up to 20% but national debt was only about 10% of National GDP.  I a baby boomer was about 20 years old.  I’m at the end of the baby boomers.  Now national debt say $33T, without undocumented debt of say $130T.  National debt is now a multiple of National GDP so interest rates can’t stay high or for long since we can’t afford to pay it.  I am now 62 and “You” owe me and my large group of Baby boomers that $130T.  For each 4 of us retiring there is only one of you replacing us.  Are “You” willing to work 4 times harder than we did and lay more taxes?

    We have evaluated, sold, refinanced our properties/debt to reduce our risk factor.  If politics and the result go bad.

    We have bought 3 new pieces of land and have two sitting in the wings.  Working in zoning, utilities, infrastructure. Will sit on them. If politics goes positive we will explode with development. 

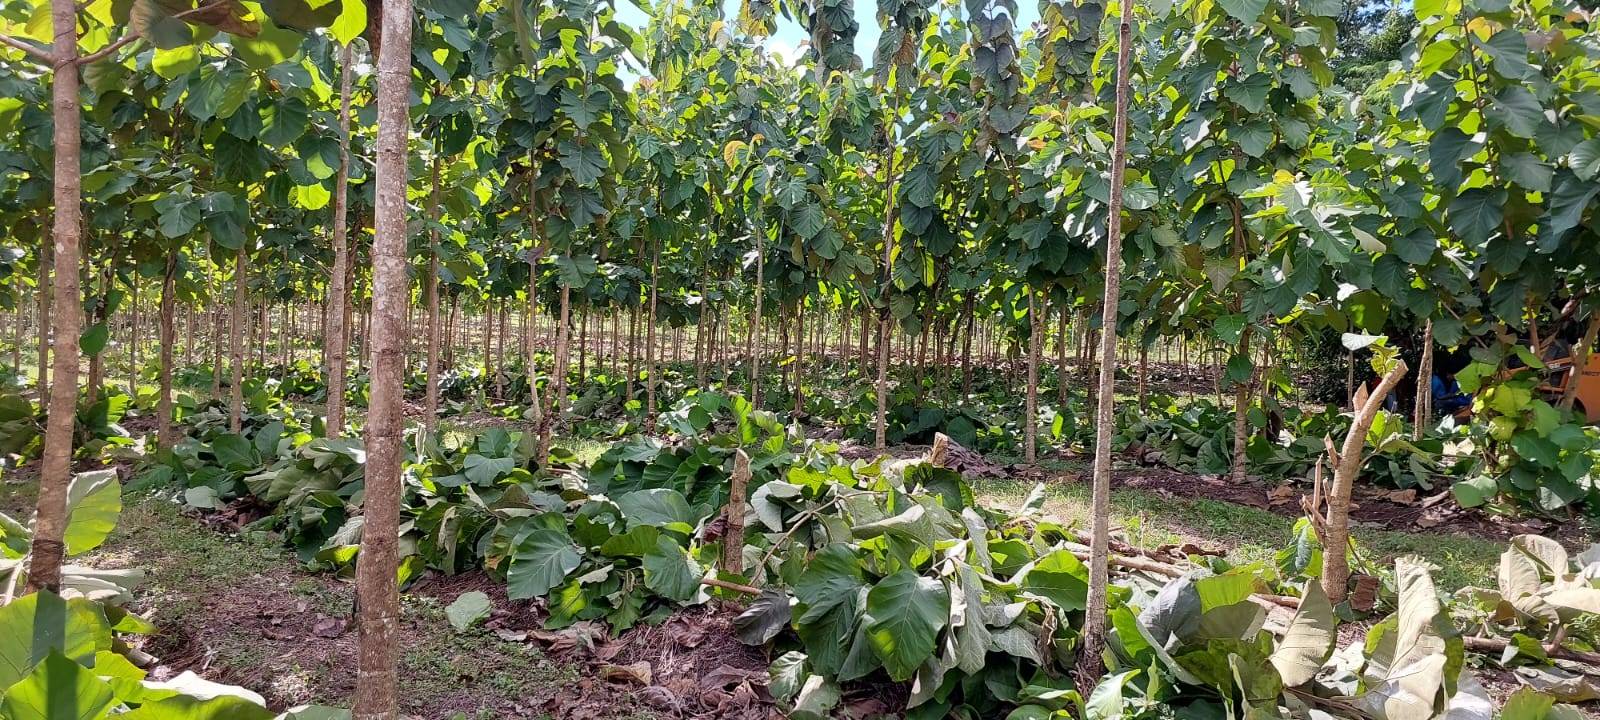
    Bridging continued bad environment we have Teak trees.  Our market will be China, India or Europe.  Different markets than the US.  Also Teak trees aren’t perishable. If it’s a bad economy we just let them keep growing and adding value.  

    Inflation and interest rates go up, we make money.

    Inflation and interest rates go down, we make money.  

    Guys just trimmed limbs at our place in Belize.  These are 3 years old.  Just what you see will be worth $500k in 20 years.  If the economy is bad then we wait 5 years and they are worth $700k.
  • Henry ClarkPro Member
    Developer · Member since 2020 · 4k+ posts · 4k+ votes
    3y

    Let’s say the US goes in the toilet for whatever reason.  

    1. REI is about location, location, location. I'll state the obvious, we are in the US (location). The world wants to invest in the US. More buyers, the higher our REI prices in both upturns and downturns. The following will sound obvious to you, but it's not true all of the world.

    A.  Innocent until proven guilty.  Versus guilty until you prove you’re innocent.

    B.  Property ownerships rights

    C.  Clear title process

    D.  Democratic Republic

    E.  Rule of law versus Rule of man.

    F.  Have approx 50% ocean access, loads of building and manufacturing material, tons of all kinds of energy sources.

    G.  Most importantly we have more food production than we need.

    H. We get downgraded and BRICS takes over as the currency. Saudi Arabia even want to join. 1. They don't have enough gold reserves compared to the US. Realize people are talking digital currency but that won't create a fiat currency. 2. Their economies and governments are either not stable or are tied to the US economy. 3. Their economies are not large enough. Someone will say how about China. China's economy is tied to the U.S. Also a significant portion of their economy is tied to REI and infrastructure expansion which is collapsing. Plus their population is in melt down and aging out. China is 90% desert and is resource poor. 4. Russia is a walking dead country. Broken education system, drugs, alcoholism and disease issues.

    US looks good even if it is bad.. Question is how do you ride 20 years for it to self correct.  But if you plan for the worst you would go 100% liquid and lose out in returns.  
    .   
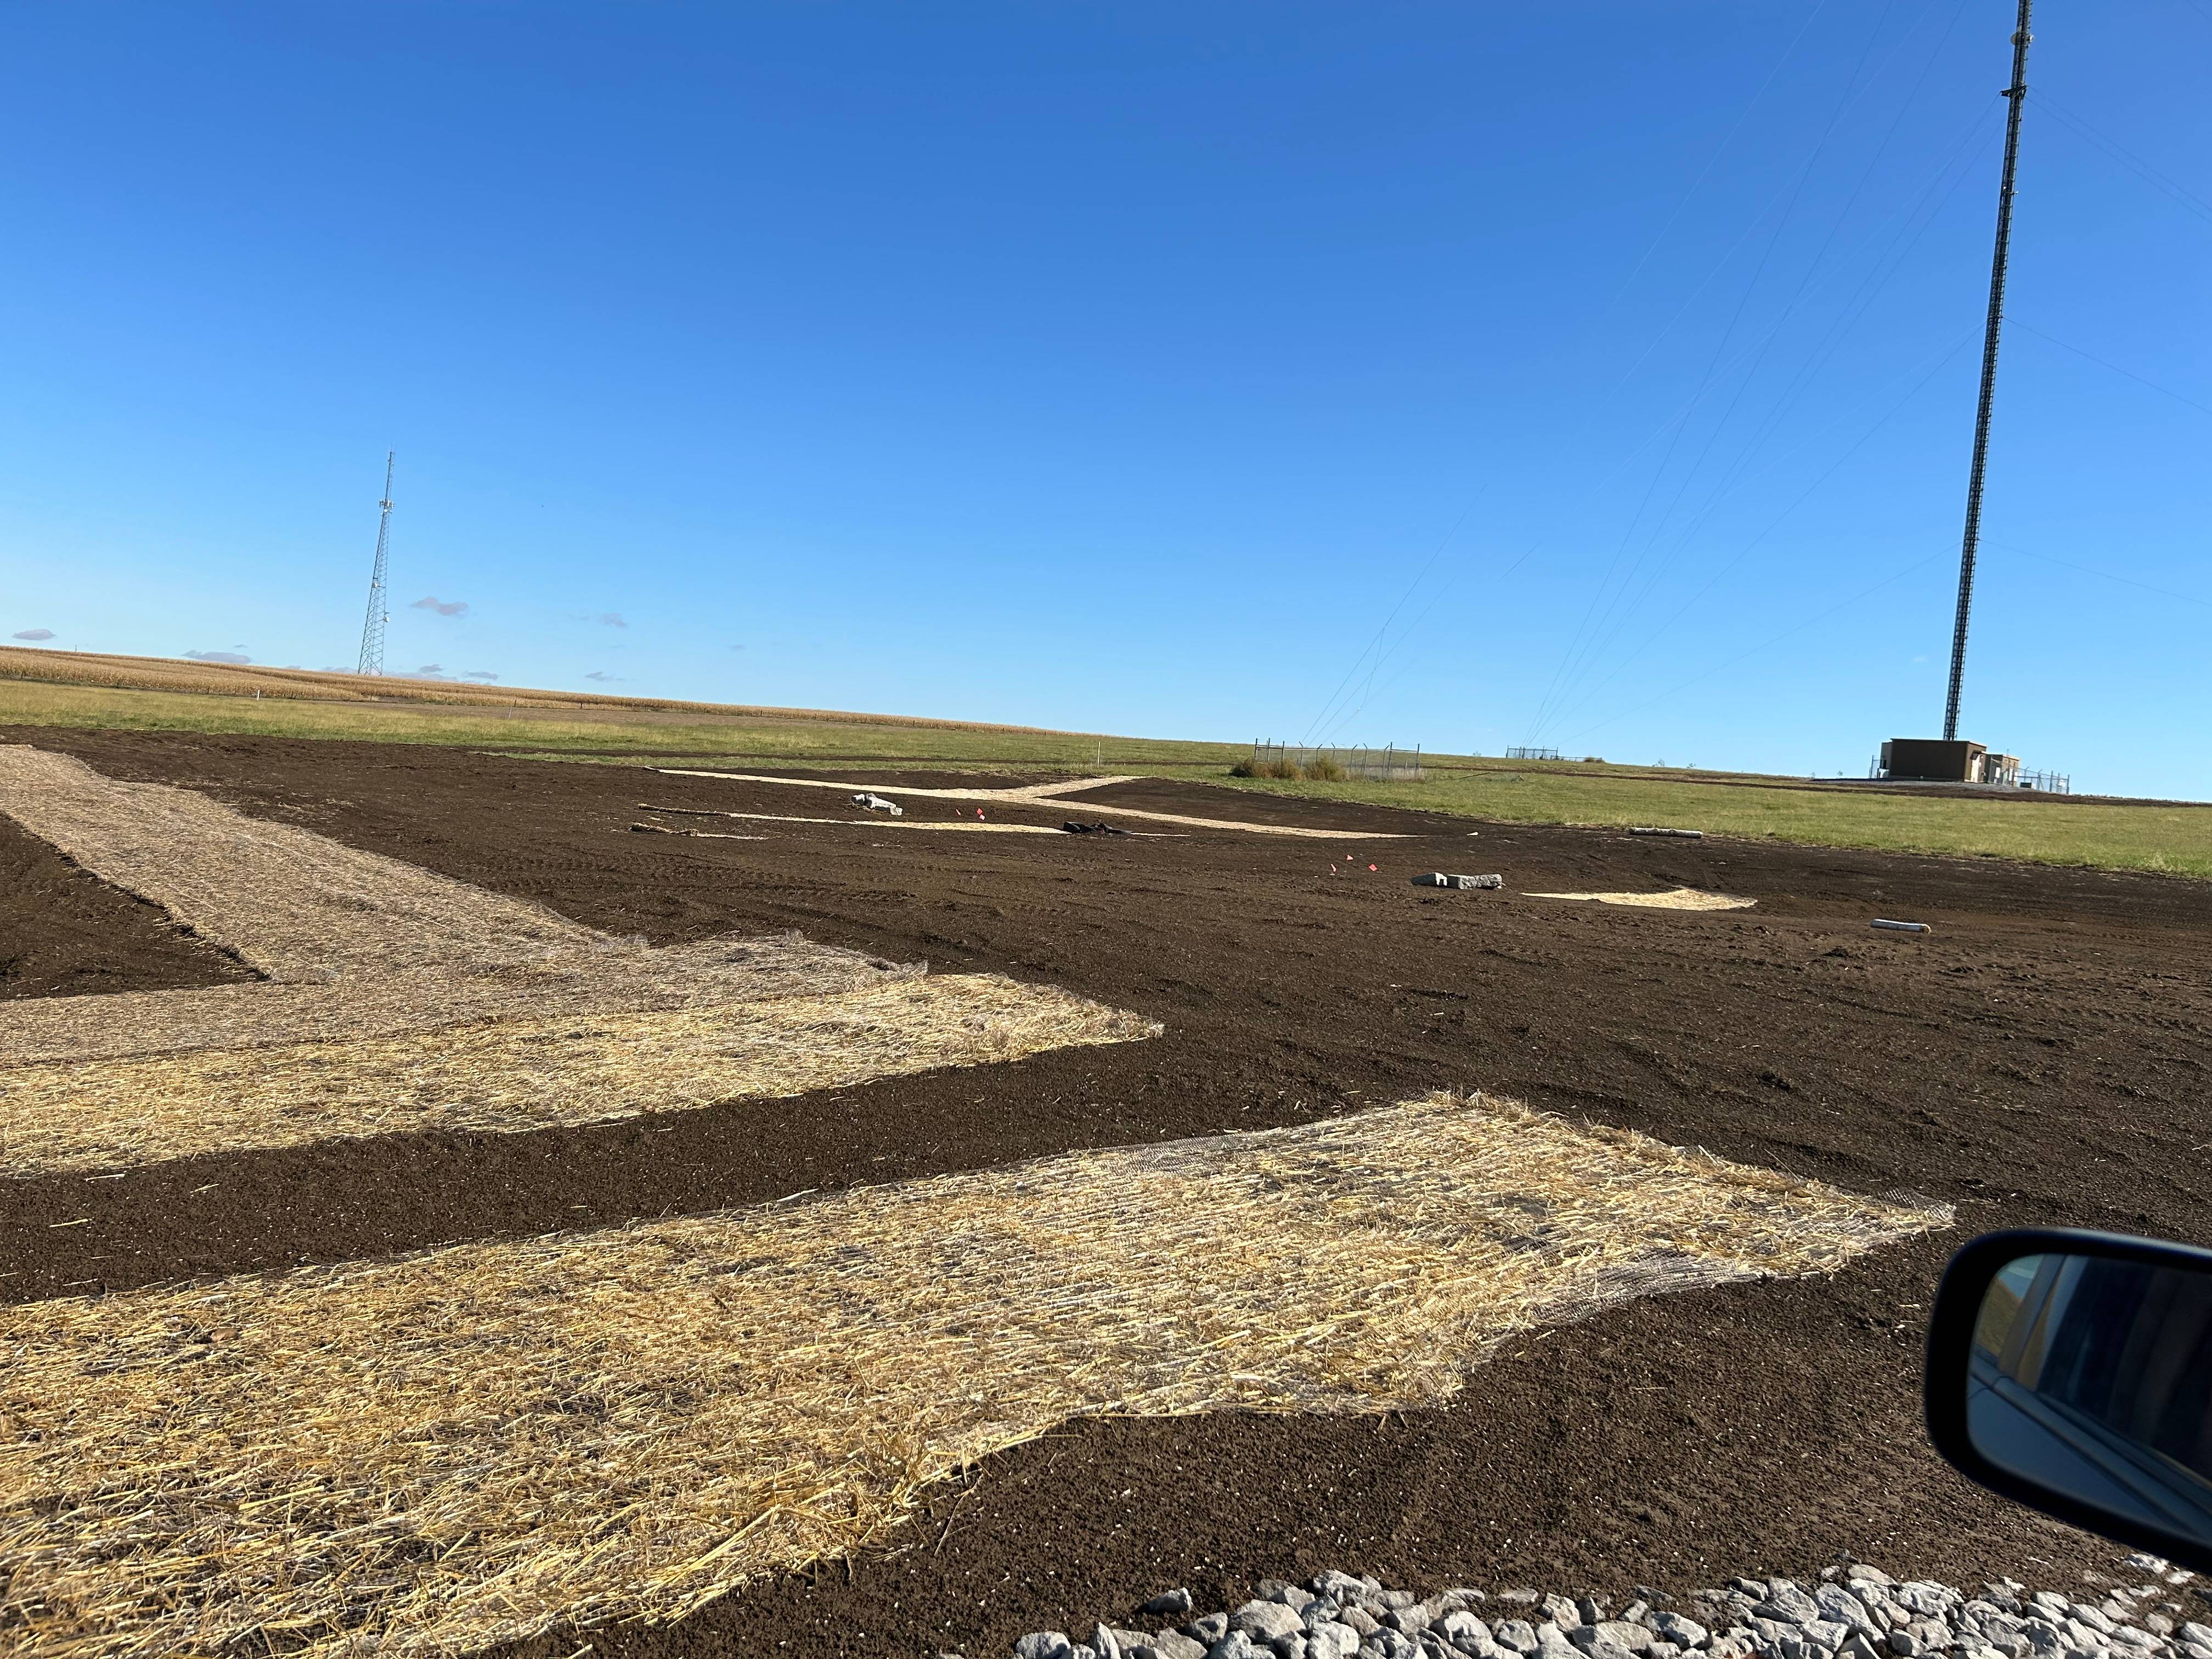
    Well back to work.  Had a great rain last night.  Have to finish spreading more grass mat.  Killing time posting waiting on the ground to dry some.  One of our sites we bought for $48k, prepping to list for $200k.  
    No bathrooms, no toilets, no tenants.
  • Rental Property Investor · East Wenatchee, WA · Member since 2014 · 10k+ posts · 16k+ votes
    3y

    An interesting tidbit about a government shutdown affecting closings-  flood insurance policies can't be issued.  Could affect up to 1300 closings per day I guess. 

    As if transactions need an additional speed bump/ wall.   

Join the conversationCreate a free account to reply, vote on answers and follow this thread.