WARNING for LA Investors: My Bad Experience with MoFin Lending

WARNING for LA Investors: My Bad Experience with MoFin Lending

Member since 2025 · 11 posts · 11 votes

I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. 

 Just hoping to save someone else from wasted time, money, and stress.

PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. 


6
Topic locked
534 views

Most Popular Reply

George DespotopoulosBusiness Member
Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
1y

Hanna, your bad experience is a bit of a false narrative. We didn't change terms on you. You were buying a property for $935k, putting $50k into it, and expecting an ARV of $1.95mm. The appraisal as-is value came in at $915k and the ARV $980k. This on paper was a very bad/unprofitable deal and I still tried to find you a solution but you refused to hear me out. I didn't change terms, I first said to challenge the appraisal but you wanted no part in it. And ultimately the property sold for $1.1mm vs your $1.95mm estimate and the appraiser's $980k (appraiser was closer than you were on that re-sale price).

I'm the co-founder/owner, normally don't get involved on new submissions but because your deal was around the holidays, and we had people out, I personally got involved, gave you competitive terms and oversaw your loan. I've funded over 2,000 transactions in 10 years and have done $600,000,000 in debt. You are literally the first negative review, which is impressive.

Things didn't go smoothly until 3 days before...from the beginning it was rocky, but we didn't let that impact you. You actually told us you've done way more deals and exited more projects then you actually have (I have the email, 4 flips and 4 rehab-to-hold/rent projects was represented). Yet, because I was involved and am able to make this discretionary call, we kept the same terms/rates/fees. 

Then, when the appraisal came in, you said the ARV would be $2.1mm, the appraiser came back and projected it to be $980k....At that stage, NOTHING changed, I had called you and explained we can challenge the appraiser's determination of ARV, you just need to provide 2-3 comps to back up the $2.1mm. At that stage you started, seemingly, crying and saying you don't trust me....Then, I said OK so forget the challenge, let's just lend against the as-is value/purchase price and disregard the renovation portion of the loan since you said you'd fund that with cash and don't need reno funds...

I'd love to open it to the group who chimed in here, how is this MoFin's fault? Borrower says ARV is $1.95mm...appraiser says $980k....we don't just take the appraiser's word, because maybe the appraiser's off, so instead, we ask the poster here, "can you send us the comps for the $1.95mm value?" And this individual refuses...All we asked were for comps to challenge. And said if it's unsuccessful, because we can't exceed 75% ARV, it would lower the initial funding amount we're able to lend. Regardless, spoiler alert, the property sold for $1.1mm.


To add, I emailed and told the original poster, I would personally refund $300, the cost for background/credit/flood cert, out of my own pocket as a sign of good faith and that I was very sorry it didn't work out. 

I'm not looking to argue, I'm just stating facts. I have all the emails to back this up. 


MoFin Lending4.9152 Reviews
5
Topic locked
See this reply in the discussion

24 Replies

Jump to latestLatest
  • Lender · Santa Monica · Member since 2025 · 28 posts · 12 votes
    1y

    Sorry to here about this Hanna, glad east street was able to pull through. I see lenders lower there internal value all the time, but to do it that late is absurd. Hoping the project goes well! 

    0
    Topic locked
    • Member since 2025 · 11 posts · 11 votes
      1y
      Quote from @Dante Craig:

      Sorry to here about this Hanna, glad east street was able to pull through. I see lenders lower there internal value all the time, but to do it that late is absurd. Hoping the project goes well! 


       Thanks-I actually didn't end up going with Easy street time. I went with another lender I've worked with before. I've worked with Easy street before, but after what happened with the lien/title issue, I'll never work with them. Easy street completely avoids responsibility when real problems occur. This customer service is useless-the only way to get anything done is by involving regulators or suing them in small claims court.

      0
      Topic locked
  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    1y
    Quote from @Hanna Zhang:

    I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

    A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

    The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.


    To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

    In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. 

     Just hoping to save someone else from wasted time, money, and stress.

    PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. 


     Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 

    7e investments53 Reviews
    1
    Topic locked
    • Jay HinrichsBusiness Member
      Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
      1y
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      dont shop lenders when you have a good one then your good one comes to the rescue.. this is your fault end of the day.. Also do you know if the NY lender was properly licensed to even do bizz in CA.. many east coast lenders do not realize the license requirements out west.
      0
      Topic locked
    • Chris SeveneyBusiness Member
      Moderator
      Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
      1y
      Quote from @Jay Hinrichs:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      dont shop lenders when you have a good one then your good one comes to the rescue.. this is your fault end of the day.. Also do you know if the NY lender was properly licensed to even do bizz in CA.. many east coast lenders do not realize the license requirements out west.

       Yes California is a bear (pun intended) - as I have been in submission/review for a year to get our CFL license for california so we can originate in CA.

      7e investments53 Reviews
      0
      Topic locked
    • Member since 2025 · 11 posts · 11 votes
      1y
      Quote from @Jay Hinrichs:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      dont shop lenders when you have a good one then your good one comes to the rescue.. this is your fault end of the day.. Also do you know if the NY lender was properly licensed to even do bizz in CA.. many east coast lenders do not realize the license requirements out west.

       I think you made a really good point. I did check-this company is licensed in California. But honestly, I don't think they understand the loan market in LA at all. I didn't have much experience last year either, but now I've really come to understand the differences between the east and west coast. at this point, i only work with lenders i know and trust. 

      0
      Topic locked
    • George DespotopoulosBusiness Member
      Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
      1y
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      We weren't doing anything special. We also hold our fix and flip/rehab and ground-up loans on balance sheet. They're short duration and we have the liquidity for that. 

      But again, we didn't represent anything special. Borrower was fully aware of the leverage ratios (100% of renovation, up to 90% of purchase price or appraised value, lower of the two, capped at 75% ARV) and that we needed an appraisal done. That was stated numerous times via email and on the phone.

      Also our terms were not anything special, she might have been subject to a lender that was charging her above market rates...we were in the 9's. We go as low as 8% - 8.5% to experienced flippers/builders. Being in the mid/upper 9's is for investors w/ her experience. 

      MoFin Lending4.9152 Reviews
      1
      Topic locked
    • George DespotopoulosBusiness Member
      Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
      1y
      Quote from @Jay Hinrichs:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      dont shop lenders when you have a good one then your good one comes to the rescue.. this is your fault end of the day.. Also do you know if the NY lender was properly licensed to even do bizz in CA.. many east coast lenders do not realize the license requirements out west.

       We are licensed in California. Easily verified by searching on NMLS (MOFIN LENDING CORPORATION). And, this was actually provided to the original poster prior to them starting the process with us.

      We're based out of Delray Beach and have been lending nationwide since 2017.

      MoFin Lending4.9152 Reviews
      1
      Topic locked
    • George DespotopoulosBusiness Member
      Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
      1y
      Quote from @Hanna Zhang:
      Quote from @Jay Hinrichs:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      dont shop lenders when you have a good one then your good one comes to the rescue.. this is your fault end of the day.. Also do you know if the NY lender was properly licensed to even do bizz in CA.. many east coast lenders do not realize the license requirements out west.

       I think you made a really good point. I did check-this company is licensed in California. But honestly, I don't think they understand the loan market in LA at all. I didn't have much experience last year either, but now I've really come to understand the differences between the east and west coast. at this point, i only work with lenders i know and trust. 

       Hanna, with all due respect, I've done over 2,000 loans personally. My company has exceeded that with our other sales team member. We've done loans in almost every state of the United States of America, across the last 10 years. And, we've done hundred of millions in Los Angeles (even have an employee there, yay!) and even in states like Hawaii, Wisconsin, New York, Georgia, the Carolina, etc..

      I just want to point out the fact that this property you purchased for $935k, and put $50k into, you sold it for $1.1mm. That's an ROI of 11.7% without including closing costs, raltor commissions, holding costs (property taxes, insurance, utilities, financing). If make certain assumptions and factor that in, ROI likely falls to 4-6%.

      Regardless of that, I apologized that it didn't work out. And I offered to refund you the costs incurred in working with us. You didn't accept either. All good. I appreciate that you're upset and wish it didn't turn out that way but tried my best to make sure you weren't put in a bad spot. I have the emails and call logs to show that. 

      MoFin Lending4.9152 Reviews
      2
      Topic locked
    • Chris SeveneyBusiness Member
      Moderator
      Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
      1y
      Quote from @George Despotopoulos:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      We weren't doing anything special. We also hold our fix and flip/rehab and ground-up loans on balance sheet. They're short duration and we have the liquidity for that. 

      But again, we didn't represent anything special. Borrower was fully aware of the leverage ratios (100% of renovation, up to 90% of purchase price or appraised value, lower of the two, capped at 75% ARV) and that we needed an appraisal done. That was stated numerous times via email and on the phone.

      Also our terms were not anything special, she might have been subject to a lender that was charging her above market rates...we were in the 9's. We go as low as 8% - 8.5% to experienced flippers/builders. Being in the mid/upper 9's is for investors w/ her experience. 

      sounds like appraisal came in lower than expected and they did not like it, which happens a lot in todays world.

      We had a borrower asking for a cash out refinance and was listing property on market for 50% more than it was worth, then took it off market thinking appraisal would come in high, it did not and they got vvery upset saying appraisal is way off but could not provide any comps. They wanted us to reimburse the appraisal fee (we said no). 

      We also had a borrower get very close to closing then they requested the loan documents be modified (substantial revisions). Again another - sorry. 

      We have also seen it where we were selling off one of our loans and the end buyer who had given CTC on our end, so we funded it, then went to trade it to them and came back and was like "sorry we did not realize X".... 

      As many say, this is the cost of doing business. 
      7e investments53 Reviews
      0
      Topic locked
    • George DespotopoulosBusiness Member
      Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
      1y
      Quote from @Chris Seveney:
      Quote from @George Despotopoulos:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      We weren't doing anything special. We also hold our fix and flip/rehab and ground-up loans on balance sheet. They're short duration and we have the liquidity for that. 

      But again, we didn't represent anything special. Borrower was fully aware of the leverage ratios (100% of renovation, up to 90% of purchase price or appraised value, lower of the two, capped at 75% ARV) and that we needed an appraisal done. That was stated numerous times via email and on the phone.

      Also our terms were not anything special, she might have been subject to a lender that was charging her above market rates...we were in the 9's. We go as low as 8% - 8.5% to experienced flippers/builders. Being in the mid/upper 9's is for investors w/ her experience. 

      sounds like appraisal came in lower than expected and they did not like it, which happens a lot in todays world.

      We had a borrower asking for a cash out refinance and was listing property on market for 50% more than it was worth, then took it off market thinking appraisal would come in high, it did not and they got vvery upset saying appraisal is way off but could not provide any comps. They wanted us to reimburse the appraisal fee (we said no). 

      We also had a borrower get very close to closing then they requested the loan documents be modified (substantial revisions). Again another - sorry. 

      We have also seen it where we were selling off one of our loans and the end buyer who had given CTC on our end, so we funded it, then went to trade it to them and came back and was like "sorry we did not realize X".... 

      As many say, this is the cost of doing business. 
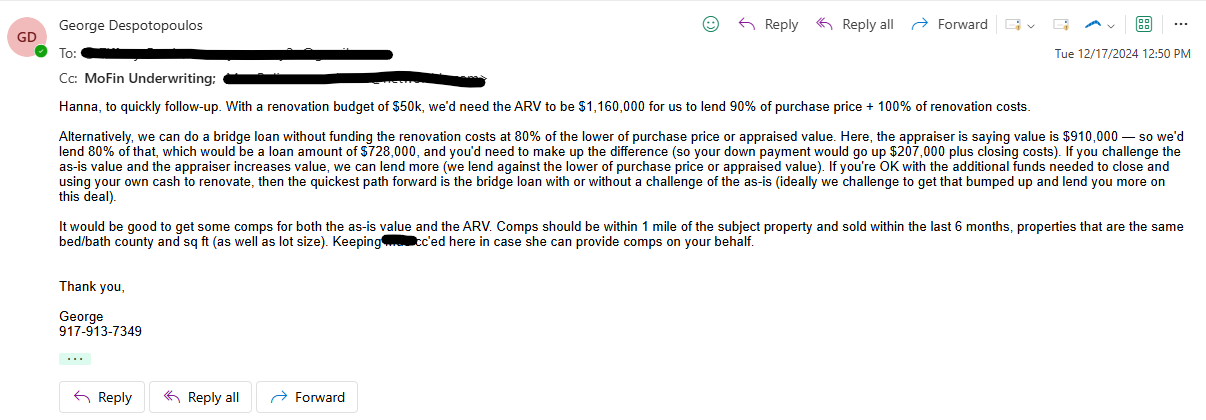
      Yes, appraisal came in literally $1 million below their projected ARV. Projected was $1,950,000, ARV was $980,000, and we still said provide comps, just get it to $1.16mm or so and we can keep everything the same. But they refused, had even cc'ed their realtor to see if they could help. No response. 

      Then we get these negative reviews on here and google, I'm like dang...I look up the property and I see they flipped it for only $1,100,000...nowhere near their projected $1,950,000 and pretty close to the appraiser's $980,000. The appraiser was a local company that's been in business for 20+ years as well and are in LA proper. And yet, we still pushed to challenge and see if we could make it work. 


      MoFin Lending4.9152 Reviews
      2
      Topic locked
    • Chris SeveneyBusiness Member
      Moderator
      Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
      11mo
      Quote from @George Despotopoulos:
      Quote from @Chris Seveney:
      Quote from @George Despotopoulos:
      Quote from @Chris Seveney:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


       Sorry to hear that but what I can tell you is think of lending as buying soda - at the end of the day it typically flows to the top 2 or 3 major companies. the same is private lending, it goes to apollo, blackstone and a few others. If someone is NOT using their balance sheet, it is very very very rare they have "special" terms because they are selling one of the products from the institution. The main difference with lenders is the points, rates vary slightly and most importantly the experience. 


      We weren't doing anything special. We also hold our fix and flip/rehab and ground-up loans on balance sheet. They're short duration and we have the liquidity for that. 

      But again, we didn't represent anything special. Borrower was fully aware of the leverage ratios (100% of renovation, up to 90% of purchase price or appraised value, lower of the two, capped at 75% ARV) and that we needed an appraisal done. That was stated numerous times via email and on the phone.

      Also our terms were not anything special, she might have been subject to a lender that was charging her above market rates...we were in the 9's. We go as low as 8% - 8.5% to experienced flippers/builders. Being in the mid/upper 9's is for investors w/ her experience. 

      sounds like appraisal came in lower than expected and they did not like it, which happens a lot in todays world.

      We had a borrower asking for a cash out refinance and was listing property on market for 50% more than it was worth, then took it off market thinking appraisal would come in high, it did not and they got vvery upset saying appraisal is way off but could not provide any comps. They wanted us to reimburse the appraisal fee (we said no). 

      We also had a borrower get very close to closing then they requested the loan documents be modified (substantial revisions). Again another - sorry. 

      We have also seen it where we were selling off one of our loans and the end buyer who had given CTC on our end, so we funded it, then went to trade it to them and came back and was like "sorry we did not realize X".... 

      As many say, this is the cost of doing business. 
      Yes, appraisal came in literally $1 million below their projected ARV. Projected was $1,950,000, ARV was $980,000, and we still said provide comps, just get it to $1.16mm or so and we can keep everything the same. But they refused, had even cc'ed their realtor to see if they could help. No response. 

      Then we get these negative reviews on here and google, I'm like dang...I look up the property and I see they flipped it for only $1,100,000...nowhere near their projected $1,950,000 and pretty close to the appraiser's $980,000. The appraiser was a local company that's been in business for 20+ years as well and are in LA proper. And yet, we still pushed to challenge and see if we could make it work. 


      We just had a borrower complain and cancel a closing because it was a STR, and even thought it had low LTV, the DSCR rate was below 1% because the rental income they projected (Gross) of $80k was around $40k. We had to re-underwrite it. Title was also clearing up some title issues and they got frustrated so just paid cash and now are upset with us because we were around the 28th day since getting the app. Cannot win with some borrowers.

      7e investments53 Reviews
      0
      Topic locked
  • Joe S.Pro Member
    Investor · San Antonio · Member since 2020 · 3k+ posts · 3k+ votes
    1y
    Quote from @Hanna Zhang:

    I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

    A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

    The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.


    To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

    In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. 

     Just hoping to save someone else from wasted time, money, and stress.

    PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. 


    Your frustration and disappointment is understandable… 

    To leave a negative review could leave real damage to a company. Did you write a positive review for the company that helped save the deal? 


    1
    Topic locked
    • Member since 2025 · 11 posts · 11 votes
      1y
      Quote from @Joe S.:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


      Your frustration and disappointment is understandable… 

      To leave a negative review could leave real damage to a company. Did you write a positive review for the company that helped save the deal? 


      This incident happened in November of last year. In the end, this company offered me the exact same terms as the lender I’ve always worked with. But I no longer trusted them, so I turned to my regular lender, and we closed the deal in just two days. At the time, I was rushing to close escrow, so I didn’t bother dealing with this company anymore, nor did I leave them a negative review.

      The reason I remembered this situation was because the company kept sending me promotional emails. That’s when I decided to leave a review.I usually don’t leave negative reviews for companies, but if I do, it means the experience was truly unbearable.
      I initially didn’t even give the company one star, yet their so-called co-founder kept arguing with me. So I changed it to one star and stopped engaging with him.Just because he’s a lawyer, he thinks he can save money by cutting customer service costs. I’m done engaging.

      I simply shared my experience and stated the facts. Whether others choose to work with this company is their own decision.

      0
      Topic locked
    • George DespotopoulosBusiness Member
      Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
      1y
      Quote from @Hanna Zhang:
      Quote from @Joe S.:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


      Your frustration and disappointment is understandable… 

      To leave a negative review could leave real damage to a company. Did you write a positive review for the company that helped save the deal? 


      This incident happened in November of last year. In the end, this company offered me the exact same terms as the lender I’ve always worked with. But I no longer trusted them, so I turned to my regular lender, and we closed the deal in just two days. At the time, I was rushing to close escrow, so I didn’t bother dealing with this company anymore, nor did I leave them a negative review.

      The reason I remembered this situation was because the company kept sending me promotional emails. That’s when I decided to leave a review.I usually don’t leave negative reviews for companies, but if I do, it means the experience was truly unbearable.
      I initially didn’t even give the company one star, yet their so-called co-founder kept arguing with me. So I changed it to one star and stopped engaging with him.Just because he’s a lawyer, he thinks he can save money by cutting customer service costs. I’m done engaging.

      I simply shared my experience and stated the facts. Whether others choose to work with this company is their own decision.

       What do you mean their "so-called founder?" I am the founder. Not so called. I built this company with a partner, we've had nothing but positive reviews until your negative one. 

      At first, I actually was pretty distraught over your negative review. I've worked very hard and have built my company on being super transparent, honest, and personable. We have exclusively 5-star reviews before your negative one. And for our first negative review to be a deal like this, where the ARV came in a million below the projected ARV by the borrower, felt a bit unfair. But is what it is. Makes us look human!

      Anyways, still open to refunding you and moving on from this :) Hope you're doing well.

      MoFin Lending4.9152 Reviews
      1
      Topic locked
    • Member since 2025 · 11 posts · 11 votes
      1y
      Quote from @George Despotopoulos:
      Quote from @Hanna Zhang:
      Quote from @Joe S.:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.


      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. 

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. 


      Your frustration and disappointment is understandable… 

      To leave a negative review could leave real damage to a company. Did you write a positive review for the company that helped save the deal? 


      This incident happened in November of last year. In the end, this company offered me the exact same terms as the lender I’ve always worked with. But I no longer trusted them, so I turned to my regular lender, and we closed the deal in just two days. At the time, I was rushing to close escrow, so I didn’t bother dealing with this company anymore, nor did I leave them a negative review.

      The reason I remembered this situation was because the company kept sending me promotional emails. That’s when I decided to leave a review.I usually don’t leave negative reviews for companies, but if I do, it means the experience was truly unbearable.
      I initially didn’t even give the company one star, yet their so-called co-founder kept arguing with me. So I changed it to one star and stopped engaging with him.Just because he’s a lawyer, he thinks he can save money by cutting customer service costs. I’m done engaging.

      I simply shared my experience and stated the facts. Whether others choose to work with this company is their own decision.

       What do you mean their "so-called founder?" I am the founder. Not so called. I built this company with a partner, we've had nothing but positive reviews until your negative one. 

      At first, I actually was pretty distraught over your negative review. I've worked very hard and have built my company on being super transparent, honest, and personable. We have exclusively 5-star reviews before your negative one. And for our first negative review to be a deal like this, where the ARV came in a million below the projected ARV by the borrower, felt a bit unfair. But is what it is. Makes us look human!

      Anyways, still open to refunding you and moving on from this :) Hope you're doing well.

      Hello George: 

      I have the right to share my experience, just as you have the right to respond.

      The facts are simple:  This forced me to contact my previous lender, who managed to complete the loan within a day and a half — a situation that nearly damaged my reputation with my agent.In addition, I never received the $300 application fee refund.

      My only point is this: you are by far the most unprofessional fix-and-flip lender I’ve worked with in Los Angeles — both in terms of loan communication and customer service. Instead of addressing the issue professionally, you were rude and argumentative, showing no concern from the client’s perspective.

      If you believe my post affects your reputation, you should focus on improving your service quality, not silencing clients.

      I sincerely hope you take this feedback to improve your business and customer service. Wishing you success in the future.

      This will be my final response.

      0
      Topic locked
    • George DespotopoulosBusiness Member
      Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
      1y
      Quote from @Hanna Zhang:
      Quote from @George Despotopoulos:
      Quote from @Hanna Zhang:
      Quote from @Joe S.:
      Quote from @Hanna Zhang:

      I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

      A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

      The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

      Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

      I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

      I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

      But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

      To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

      In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

       Just hoping to save someone else from wasted time, money, and stress.

      PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


      Your frustration and disappointment is understandable… 

      To leave a negative review could leave real damage to a company. Did you write a positive review for the company that helped save the deal? 


      This incident happened in November of last year. In the end, this company offered me the exact same terms as the lender I’ve always worked with. But I no longer trusted them, so I turned to my regular lender, and we closed the deal in just two days. At the time, I was rushing to close escrow, so I didn’t bother dealing with this company anymore, nor did I leave them a negative review.

      The reason I remembered this situation was because the company kept sending me promotional emails. That’s when I decided to leave a review.I usually don’t leave negative reviews for companies, but if I do, it means the experience was truly unbearable.
      I initially didn’t even give the company one star, yet their so-called co-founder kept arguing with me. So I changed it to one star and stopped engaging with him.Just because he’s a lawyer, he thinks he can save money by cutting customer service costs. I’m done engaging.

      I simply shared my experience and stated the facts. Whether others choose to work with this company is their own decision.

       What do you mean their "so-called founder?" I am the founder. Not so called. I built this company with a partner, we've had nothing but positive reviews until your negative one. 

      At first, I actually was pretty distraught over your negative review. I've worked very hard and have built my company on being super transparent, honest, and personable. We have exclusively 5-star reviews before your negative one. And for our first negative review to be a deal like this, where the ARV came in a million below the projected ARV by the borrower, felt a bit unfair. But is what it is. Makes us look human!

      Anyways, still open to refunding you and moving on from this :) Hope you're doing well.


      Hello George: 

      I have the right to share my experience, just as you have the right to respond.


      The facts are simple: at closing, I did not receive the terms that were originally promised. This forced me to contact my previous lender, who managed to complete the loan within a day and a half — a situation that nearly damaged my reputation with my agent.In addition, I never received the $300 application fee refund.

      My only point is this: you are by far the most unprofessional fix-and-flip lender I’ve worked with in Los Angeles — both in terms of loan communication and customer service. Instead of addressing the issue professionally, you were rude and argumentative, showing no concern from the client’s perspective.

      If you believe my post affects your reputation, you should focus on improving your service quality, not silencing clients.

      Lastly, please do not disclose my personal information — any such action will be reported to the CFPB, DFPI immediately.

      I sincerely hope you take this feedback to improve your business and customer service. Wishing you success in the future.

      This will be my final response.


      I didn't disclose your personal information...what are you referring to? The numbers on a deal? Your name is your username. No mention of a property address or where you're located...There's nothing else in any of my comments about you. Not sure what you're referring to but point it out and I'll make sure to remove from my comments. 

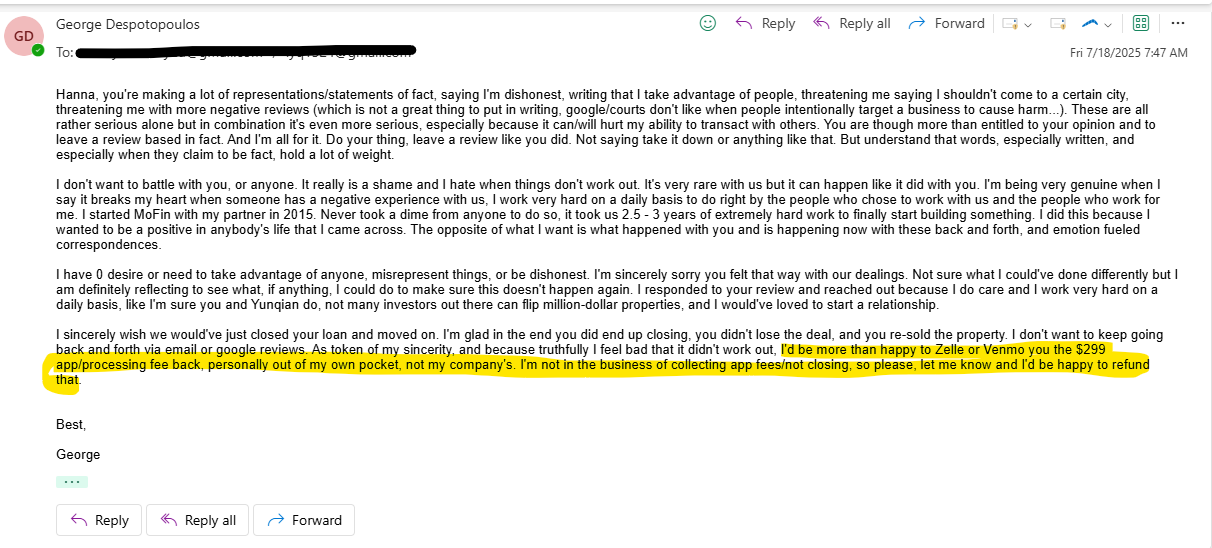
      And your terms didn't change at closing. Your terms didn't actually change. I'm attaching my email to you where I lay out exactly what I laid out above and to you on the phone. You never responded. 

      If you want your refund, just reply to my email where I offer it (see attached), and let me know where to send...

      If you've noticed, I've been nothing but communicative, responsive, and respectful, even though you've threatened me a few times with leaving negative reviews or reporting me to the CFPB and DFPI, and I even offered a $300 (well, I offered $299 to be exact, because that's the app/processing fee) refund out of my own pocket. There's no name calling from my end, yet you've called me unprofessional, rude, argumentative, etc.. Meanwhile I'm just stating facts. It seems that's what's upsetting you? A $1.1mm re-sale price, when you're projecting $1.95mm (and the appraiser is saying 980k) probably would upset me too...

      Lastly, how am I trying to silence anyone when I'm out here in the open responding and just restating the facts from my end and actually willing to provide actual evidence of what occurred? 

      I think you've seriously got the wrong read on me. I love what I do and started MoFin from nothing with my partner. I'm not upset with what you're writing, in part because it's so off from reality, but I do think it's a bit 1-sided and you're kind of distorting the facts/truth, so I think it's fair to present things from my end. I've enjoyed working in this industry for 10 years now and have had nothing but overwhelmingly positive experiences with real estate investors across the country. And it's because I genuinely care and respect anyone who elects to work with me and my company. If that's not coming through to you, then we'll never see eye to eye, and that's fine. Not everyone can like me, as much as I try, and I've accepted that. 

      I've built a career making moves for people and doing right by everyone I encounter. Not to get all hippie, but I am a big believer in karma, and I just want to live my life in a way that I'm proud of. I rather be broke and poor than make a living that's not completely honest and good intentioned. I come from an immigrant household where I saw my father working 6-7 days a week, yet still showing up to every soccer game, school function, and family dinner, and still go from being an employee to employer through pure work ethic & integrity. I wouldn't be able to look myself in the mirror if I didn't display the same characteristics and features  of honesty, hard-work, and respect for clients, employees, co-workers, and anyone else I encounter. 

      Speak your mind, share your experience, no one said otherwise or tried to stop you. 

      MoFin Lending4.9152 Reviews
      0
      Topic locked
  • George DespotopoulosBusiness Member
    Lender · New York, NY · Member since 2016 · 936 posts · 287 votes
    1y

    Hanna, your bad experience is a bit of a false narrative. We didn't change terms on you. You were buying a property for $935k, putting $50k into it, and expecting an ARV of $1.95mm. The appraisal as-is value came in at $915k and the ARV $980k. This on paper was a very bad/unprofitable deal and I still tried to find you a solution but you refused to hear me out. I didn't change terms, I first said to challenge the appraisal but you wanted no part in it. And ultimately the property sold for $1.1mm vs your $1.95mm estimate and the appraiser's $980k (appraiser was closer than you were on that re-sale price).

    I'm the co-founder/owner, normally don't get involved on new submissions but because your deal was around the holidays, and we had people out, I personally got involved, gave you competitive terms and oversaw your loan. I've funded over 2,000 transactions in 10 years and have done $600,000,000 in debt. You are literally the first negative review, which is impressive.

    Things didn't go smoothly until 3 days before...from the beginning it was rocky, but we didn't let that impact you. You actually told us you've done way more deals and exited more projects then you actually have (I have the email, 4 flips and 4 rehab-to-hold/rent projects was represented). Yet, because I was involved and am able to make this discretionary call, we kept the same terms/rates/fees. 

    Then, when the appraisal came in, you said the ARV would be $2.1mm, the appraiser came back and projected it to be $980k....At that stage, NOTHING changed, I had called you and explained we can challenge the appraiser's determination of ARV, you just need to provide 2-3 comps to back up the $2.1mm. At that stage you started, seemingly, crying and saying you don't trust me....Then, I said OK so forget the challenge, let's just lend against the as-is value/purchase price and disregard the renovation portion of the loan since you said you'd fund that with cash and don't need reno funds...

    I'd love to open it to the group who chimed in here, how is this MoFin's fault? Borrower says ARV is $1.95mm...appraiser says $980k....we don't just take the appraiser's word, because maybe the appraiser's off, so instead, we ask the poster here, "can you send us the comps for the $1.95mm value?" And this individual refuses...All we asked were for comps to challenge. And said if it's unsuccessful, because we can't exceed 75% ARV, it would lower the initial funding amount we're able to lend. Regardless, spoiler alert, the property sold for $1.1mm.


    To add, I emailed and told the original poster, I would personally refund $300, the cost for background/credit/flood cert, out of my own pocket as a sign of good faith and that I was very sorry it didn't work out. 

    I'm not looking to argue, I'm just stating facts. I have all the emails to back this up. 


    MoFin Lending4.9152 Reviews
    5
    Topic locked
  • Erik EstradaBusiness Member
    Lender · Member since 2022 · 6k+ posts · 1k+ votes
    1y
    Quote from @Hanna Zhang:

    I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

    A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

    The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

    Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

    I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

    I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

    But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

    To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

    In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

     Just hoping to save someone else from wasted time, money, and stress.

    PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


     Thank you for sharing this and I hope it reaches the thousands of investors that fall prey to this every day. 

    It is very common, even from reputable lenders like Easy Street Capital and Kiavi. It all depends on the Account Executive you work with. Many top-salespeople adopt this strategy and "see which one will stick" , they then switch to a different company or create a new company and repeat the same thing. It's nothing more than a quick cash grab at the investors expense. 

    It even happens in the broker-side of the business. Many bad players will tell a broker one thing and then switch it at the last minute. 

    Unfortunately there are really little protections for business purpose lending. This is why it is important, that once you find a solid lending partner, you build that relationship and don't look around unless you absolutely need to. I broker loans to only a handful of lenders that I trust and have developed a strong relationship with. In turn it provides my clients a great experience, and terms that align with their qualifications and market. 

    LuxePrivate Investments LLC 572 Reviews
    0
    Topic locked
  • Member since 2025 · 9 posts · 4 votes
    1y
    Quote from @Hanna Zhang:

    I’m a fix-and-flip investor based in Los Angeles, CA, and I want to share a disappointing and frustrating experience I had with MoFin Lending, which I hope will help others avoid similar situations.

    A few months ago, I was contacted by the founder of MoFin Lending via email. He claimed his company could offer me a better deal than my usual lender. I’ve worked with another private lender for years with no issues,Out of curiosity, I looked them up and saw that their Google reviews were all 5-star — so I decided to give them a shot.

    The founder offered me an appealing term: 10% down / 90% LTV, with low points — much better than the 20/80 terms I usually get. I was impressed and decided to move forward with a new property I was purchasing.

    Everything went smoothly until 3 days before closing — that's when MoFin told me they could no longer honor the 10/90 structure. They claimed their internal valuation came in $10K lower, so they could only offer 80% LTV.

    I was shocked. No other lender I’ve worked with has ever pulled this kind of last-minute change. When I raised my concerns, the founder accused me of "playing games." I wanted to ask — who's really playing games here?

    I refused to accept the 80% offer because I felt deceived. I lost $300 in application fees, but thankfully my previous lender was able to close the deal within 2 days and save the transaction.

    But it didn’t stop there. I left a negative review on Google to share my experience — and instead of a professional response, MoFin publicly replied with blame. MoFin even rated me as a “difficult client” — seriously? I paid them, not the other way around. I later updated my Google review to make it clear: I’m not here for arguments — your explanation doesn’t change the facts. MoFin clearly couldn’t accept the criticism and retaliated by publicly disclosing my personal information— all because I left a bad review. And from start to finish, not a single word of apology. Their customer service was disrespectful throughout the process.

    To be fair, this company is based in New York, and maybe their standards or processes differ from those on the West Coast. But I’ve worked with Easy Street Capital (based in Texas), and never had this kind of issue.

    In short: if you're an LA-based investor and receive an unsolicited offer from MoFin Lending promising better terms — proceed with extreme caution. What looks good on paper can fall apart when it matters most.

     Just hoping to save someone else from wasted time, money, and stress.

    PS: And if the founder of MoFin sees this post — no explanation is necessary. I’m simply stating the facts. Besides, If you disclose my personal information on this forum in retaliation for my negative review, I will file a complaint with the appropriate financial regulatory authorities.


     I have had a biggerpockets account for a while now but only lurk, I do not post. 

    I have worked with mofin lending before and found George and his team, like Rebecca, very helpful. They have always respondeed to my questions quickly and we always close when I need to and at the terms they promised. They have gone above and beyond for me even lowering my rate once when I did not expect it. 

    I do nt share any experience sdimilar to you and actually have found them to be better than most hard money lenders in the Industry. 

    George thank you for being a trusted partner, without you I would not have the portfolio i do. your team is always the best and i am refinancing one with Dave right now. I will call you tomorrow. 

    Goodnight,

    3
    Topic locked
  • Rental Property Investor · Towson, MD · Member since 2015 · 49 posts · 27 votes
    1y

    I’ve worked with MoFin nearly ten times across my portfolio, and they’ve consistently been one of the most straightforward lenders I’ve dealt with. Their process is transparent, their rates are highly competitive, and there are no hidden fees or last-minute surprises.

    From what it sounds like, the original poster may have run into a personal underwriting issue, not a bait-and-switch. That kind of situation can happen with any lender — even when purchasing a personal residence. If an appraisal comes in lower than the PP, for example, you’re required to cover the difference in cash or challenge the appraisal.

    In fact, I’ve had that happen myself — I appealed a low appraisal using my own comp set and got it successfully adjusted upward. I’ve also referred several colleagues in my network to MoFin, and every one of them has had a smooth, professional experience from start to finish.

    I worked with George back when he only had 3 people at the company, I’ve never had a bad experience. I’d continue to recommend MoFin to any investor. 

    4
    Topic locked
  • Member since 2025 · 1 post · 3 votes
    1y

    I have been in the industry for 10+ years, and I haven't encountered a lender like George and MoFin. I have worked for and with a number of hard money lenders, but the level of honesty/transparency and just overall delivery are unmatched.

    I completely understand the original posters situation and as like Gabe mentioned, that type of scenario can happen to any lender. The value really dictates a lot what can and can't be done on a loan transaction, but it's about being open and honest and communicative during the process which can really make or break the experience. The lender does not control the value of the asset, but it controls the leverage/risk management towards the project.

    I have successfully originated over 150 million in loan transactions, and can tell you from firsthand experience, George and MoFin do an excellent job with delivery and execution.

    3
    Topic locked
  • Investor · Tampa, FL · Member since 2011 · 2k+ posts · 3k+ votes
    11mo

    I don't have a dog in this fight, and have not used MoFin personally, but I have a good friend who has used them multiple times and had a good experience. 

    2
    Topic locked
  • Laurent UrichPro Member
    Member since 2024 · 43 posts · 11 votes
    11mo

    I am not familiear with the Hanna nor Mofin, and I am sorry to hear that things didn't work out.

    All I can say is that communication and expectations are key, and that I wish both of them all the best in their future endeavors.

    0
    Topic locked